




Financial News
Onterris (NYSE:ONT) reports strong Q3 2026

Environmental services provider Onterris (NYSE: ONT) reported revenue ahead of Wall Street’s expectations in Q3 2026, but revenue fell by 9.7% year on year to $203 million. Its non-GAAP profit of $0.56 per share was 34.9% above analysts’ consensus estimates.
For more on Onterris, read our free full research report.
Onterris (ONT) Q3 2026 highlights:
- Revenue $203 million vs S&P analysts’ consensus estimates of $197 million (9.7% year-on-year decline, 3.1% beat)
- Adjusted EPS $0.56 vs S&P analysts’ consensus estimates of $0.41 (34.9% beat)
- Adjusted EBITDA $35.9 million vs analysts’ consensus estimates of $34.6 million (17.7% margin, 3.8% beat)
- Operating margin 6%, up from 4.8% in the same quarter last year
- Free cash flow margin 19.7%, up from 9.9% in the same quarter last year
- Market capitalization $551 million
Onterris President and Chief Executive Officer Vijay Manthripragada commented, “Our third-quarter results demonstrate meaningful progress against our objectives for the year. Compared to prior year, we delivered higher Adjusted EBITDA, record consolidated margins and stronger cash generation despite lower reported revenue due to the normalization of episodic environmental emergency response-related recovery services. Strong growth in core consulting and water treatment services reinforces the underlying demand for our solutions, while improved project execution, favorable business mix and cost discipline are strengthening the profitability of our platform. In addition, we restarted acquisitions, with three small and highly accretive transactions completed during the second half of this year. We expect to continue our acquisition strategy, while maintaining our leverage goals.”
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Onterris’s revenue grew at a decent 8% compounded annual growth rate over the last five years. Its growth was slightly above the average industrials company and shows its offerings resonate with customers.
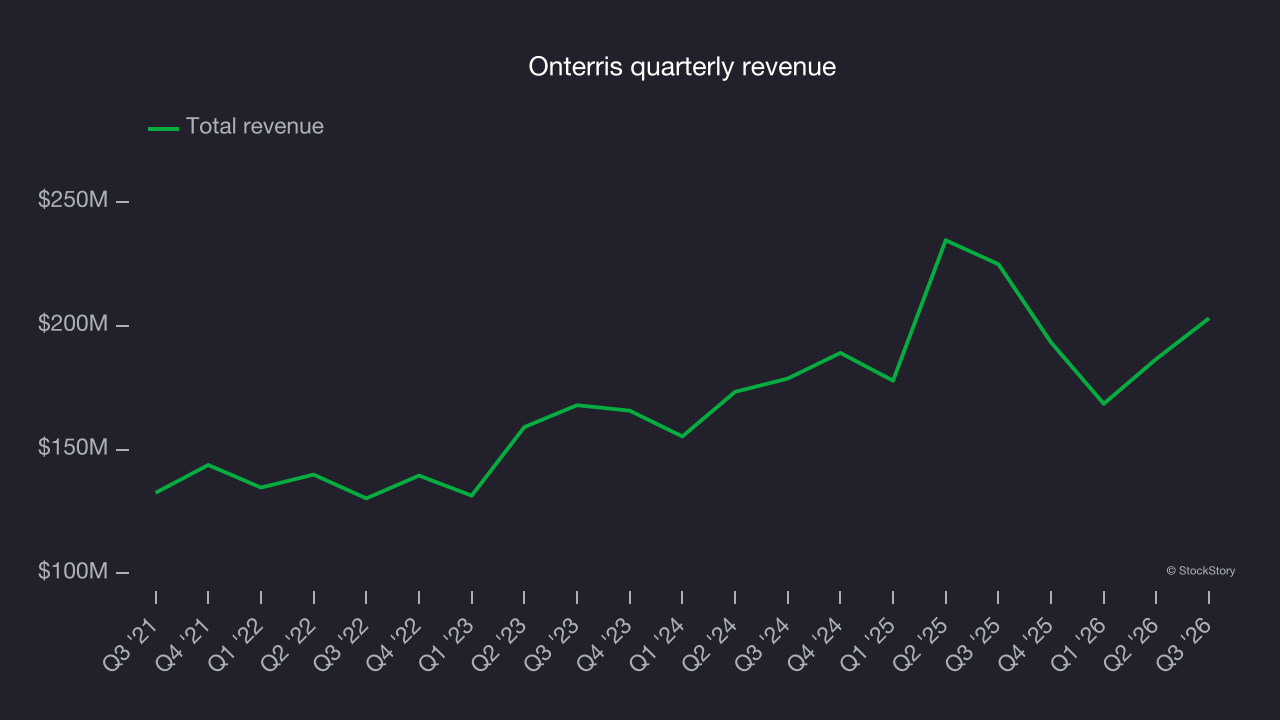
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Onterris’s recent performance shows its demand has slowed as its annualized revenue growth of 5.7% over the last two years was below its five-year trend. Decelerating revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 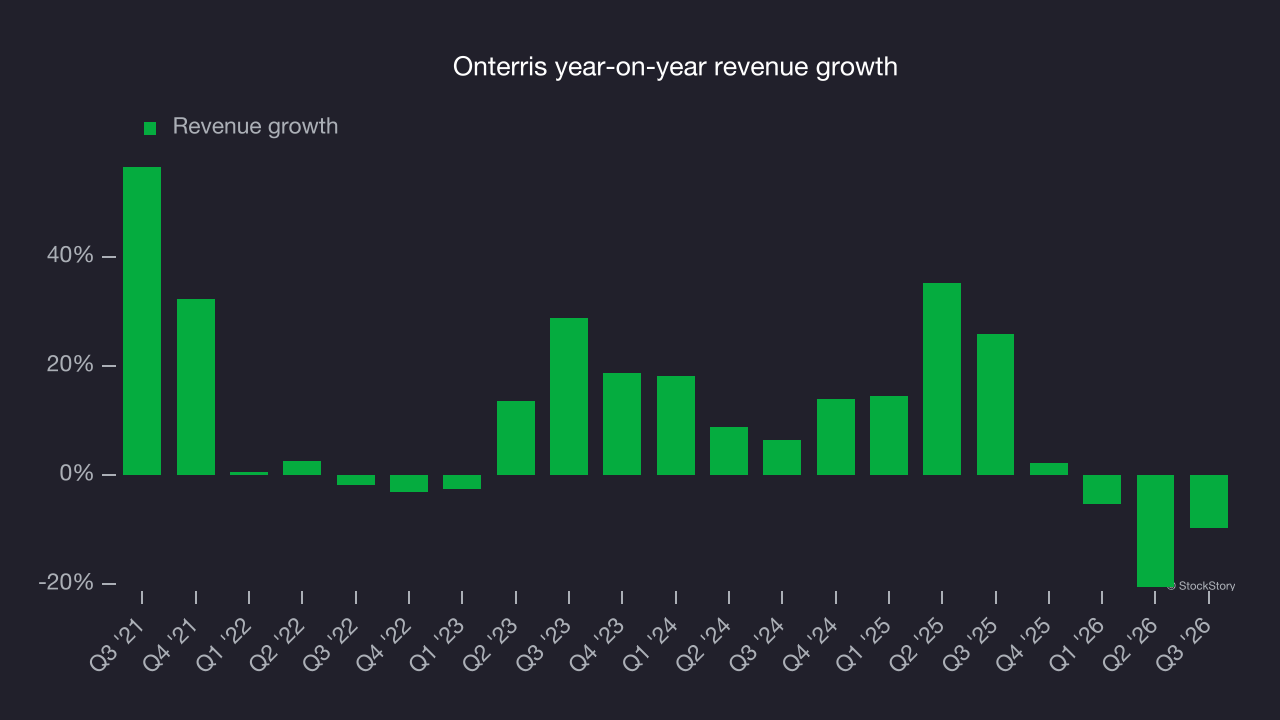
This quarter, Onterris’s revenue fell by 9.7% year on year to $203 million but beat Wall Street’s consensus estimates by 3.1%.
Looking ahead, sell-side analysts expect revenue to grow 6.2% over the next 12 months, according to S&P, similar to its two-year rate. This projection is underwhelming and indicates its newer products and services will not accelerate its top-line performance yet.
Operating margin
Although Onterris was profitable on an operating basis this quarter, it has generally struggled over a longer period. Its expensive cost structure has contributed to an average operating margin of negative 1.5% over the last five years. Unprofitable industrial companies require extra scrutiny because they could be vulnerable in a downturn. That raises doubts about the business’s ability to endure a full cycle.
On the positive side, Onterris’s operating margin rose by 5 percentage points over the last five years, as its revenue growth provided operating leverage. Still, it will take much more for the company to show consistent profitability.
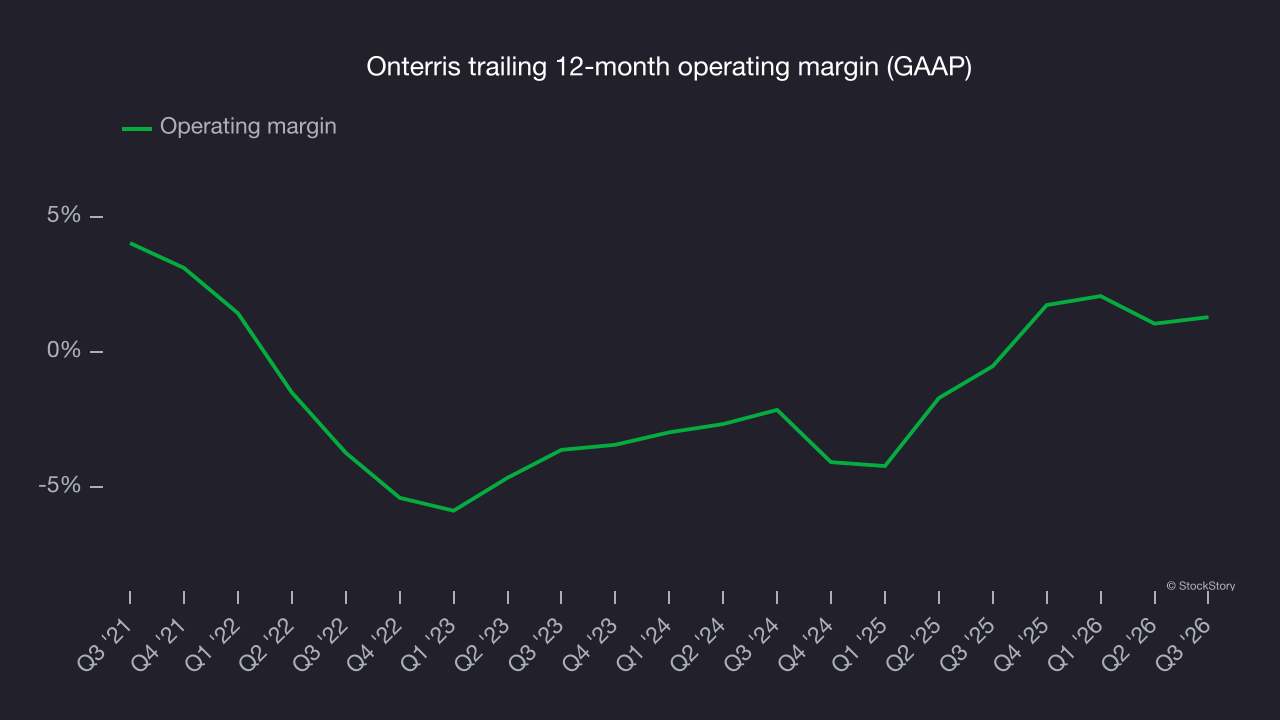
In Q3, Onterris generated an operating margin of 6%, up 1.3 percentage points year on year. Its gross margin expanded more than its operating margin, indicating that leverage on its cost of sales was the primary driver of the recent efficiency gains.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Onterris’s EPS grew at a 55.4% compounded annual growth rate over the last five years, higher than its 8% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
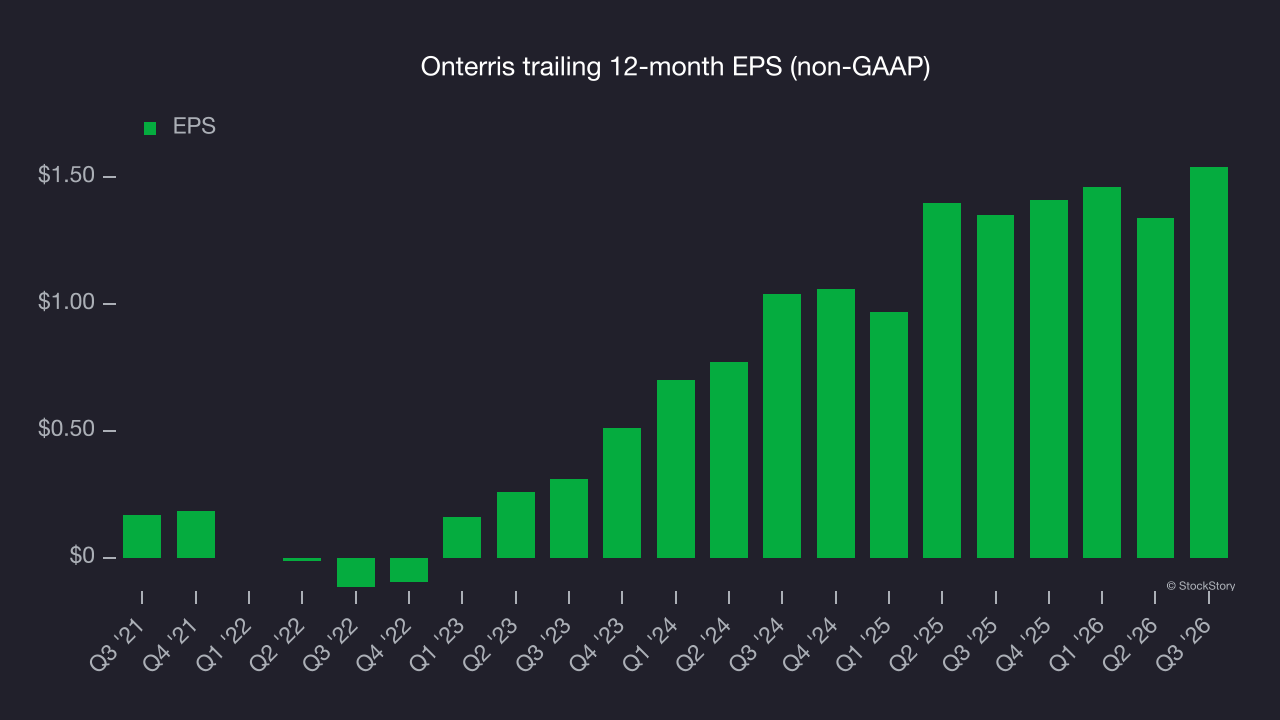
A closer look at Onterris’s earnings quality helps explain the drivers of its performance. As mentioned earlier, Onterris’s operating margin expanded by 5 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
As with revenue, examining EPS over a more recent period can provide insight into an emerging theme or development for the business.
For Onterris, its two-year annual EPS growth of 21.7% was lower than its five-year trend. Even so, its growth remained solid.
In Q3, Onterris reported adjusted EPS of $0.56, up from $0.36 in the same quarter last year. This result came in well above analysts’ consensus estimates, a positive outcome for shareholders. Over the next 12 months, Wall Street expects Onterris’s full-year EPS to shrink by 2.3% from $1.54 to $1.50, according to S&P.
Key takeaways from Onterris’s Q3 results
Onterris delivered some important positives in Q3, with both EPS and revenue topping analysts’ consensus estimates. Shares remained flat at $16.14 immediately after the results.
Onterris had a solid quarter, but is the stock a buy? When making that decision, it’s important to consider its valuation and business quality as well as the latest quarterly results. For more on Onterris, read our full research report here (it’s free).
If you believe this article contains misleading, harmful, or spam content, please let us know.
Report this articleMore News
View More
Recent Quotes
View MoreQuotes delayed at least 20 minutes.
By accessing this page, you agree to the Privacy Policy and Terms Of Service.











