




Financial News
Murphy Oil (NYSE:MUR) reports upbeat Q3 2026

Oil and gas producer Murphy Oil (NYSE: MUR) reported Q3 2026 results topping the market’s revenue expectations, with revenue up 15.9% year on year to $849.2 million. Its non-GAAP profit of $1.08 per share was 25.3% above analysts’ consensus estimates.
For more on Murphy Oil, read our full research report, available free.
Murphy Oil (MUR) Q3 2026 highlights:
- Revenue $849.2 million vs S&P analysts’ consensus estimates of $786.4 million (15.9% year-on-year growth, 8% beat)
- Adjusted EPS $1.08 vs S&P analysts’ consensus estimates of $0.86 (25.3% beat)
- Operating margin 30.2%, up from 0.8% in the same quarter last year
- Free cash flow margin 8.7%, down from 21.9% in the same quarter last year
- Oil production per day down -10.6% year on year
- Market capitalization $5.66 billion
“The results we delivered this quarter reflect our ability to create value at every stage of the asset life cycle. From finding oil to efficiently bringing it online and reliably operating our assets, this breadth of capabilities is what differentiates Murphy,” stated Eric M. Hambly, President and Chief Executive Officer.
Revenue growth
A company’s long-term performance can give signals about its business quality. Even a poor business, especially in a cyclical industry, can perform well for a year or so, but a high-quality one should exhibit resilience through cycles. Over the last five years, Murphy Oil grew its revenue at a decent 10.6% compounded annual growth rate. Its growth was slightly above the average energy upstream and integrated energy company and shows its offerings resonate with customers.
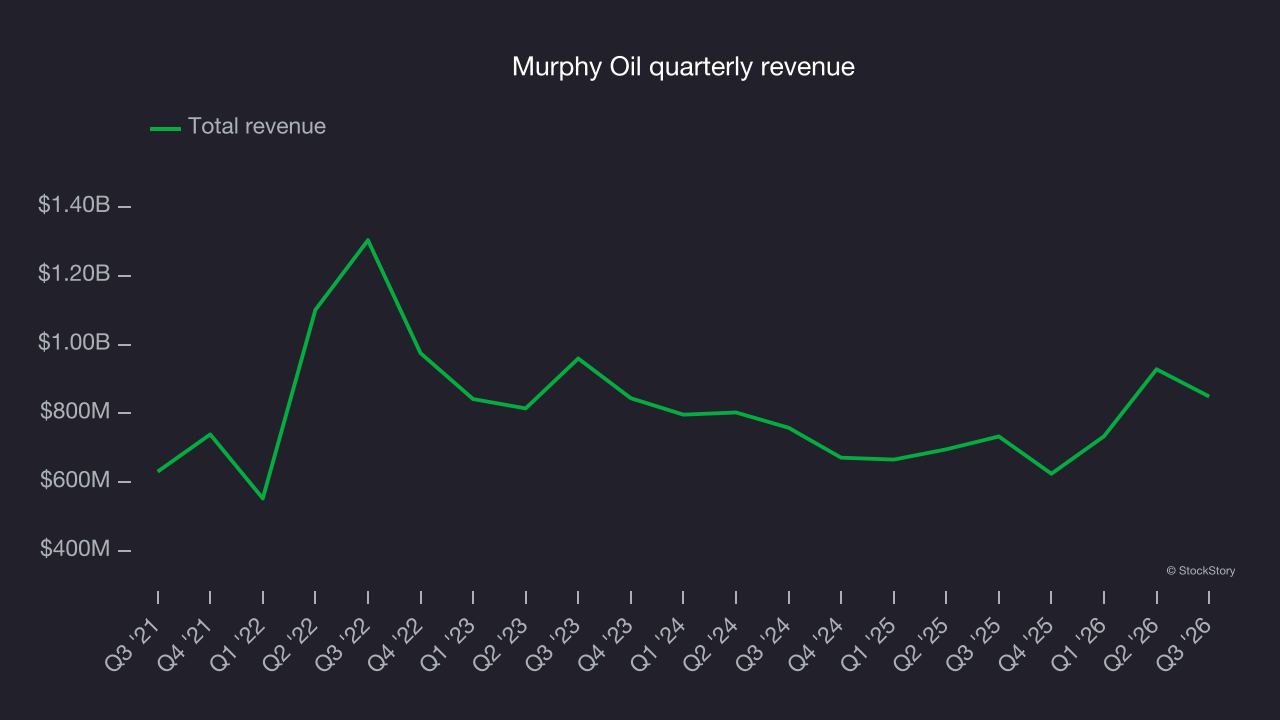
Within energy, a single time frame, even a long one, only sheds light on how well a company rode the last commodity cycle. To better assess whether a company compounds through cycles, a ten-year view provides an additional check. Murphy Oil’s annualized revenue growth of 4.5% over the last ten years is below its five-year trend, but the results were still good.
While looking at revenue is important, it can also introduce noise around commodity prices and mergers and acquisitions. Analyzing production, on the other hand, highlights what is happening inside the asset base and whether the economic footprint of a company is expanding. Over the last two years, Murphy Oil’s oil production per day declined by an average of 2.4% year on year, while its natural gas production per day was flat. 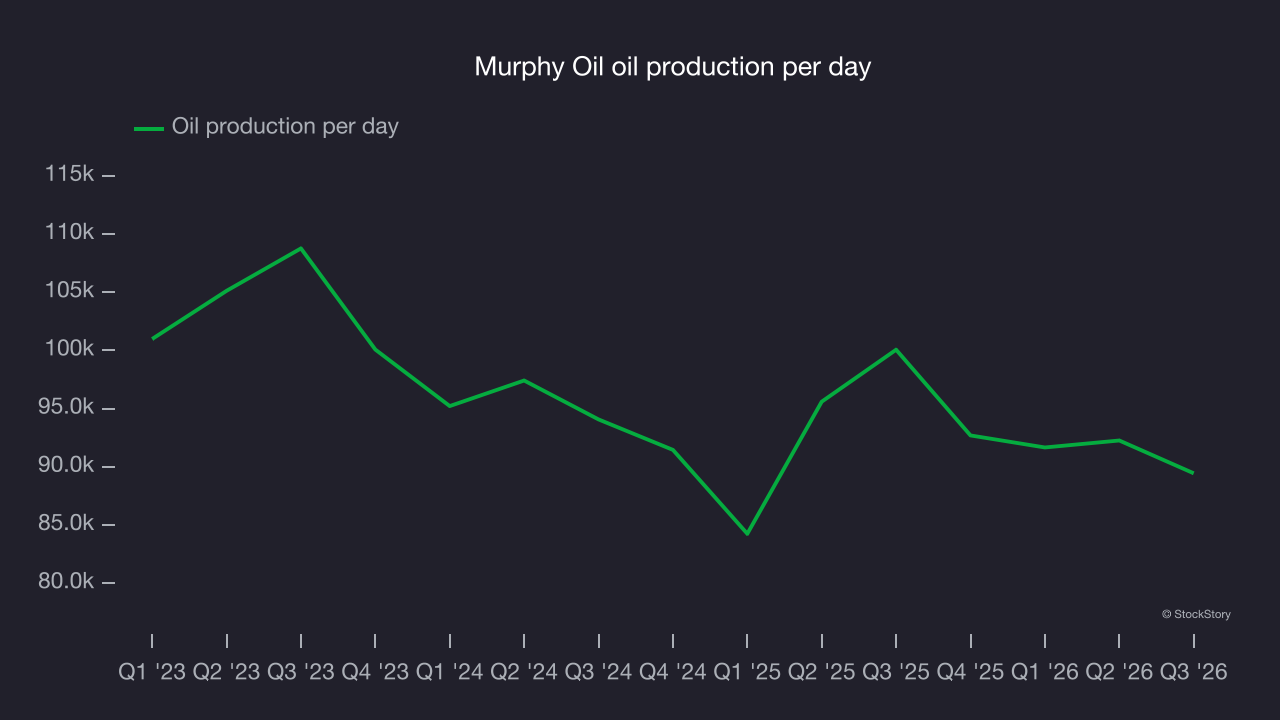
This quarter, Murphy Oil reported year-on-year revenue growth of 15.9%, and its $849.2 million of revenue exceeded Wall Street’s consensus estimates by 8%. Its oil production per day fell by 10.6% year on year.
Adjusted EBITDA margin
Adjusted EBITDA margin measures the operating profitability of an energy producer by removing accounting effects related to depletion and capitalized drilling costs. It reveals how much cash the asset base generates before capital structure and reinvestment requirements shape reported earnings.
Murphy Oil has been an efficient company over the last five years. It was one of the more profitable businesses in the energy upstream and integrated energy sector, with an average EBITDA margin of 54.5%.
Looking at the trend in its profitability, Murphy Oil’s EBITDA margin might have fluctuated slightly but has generally stayed the same over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
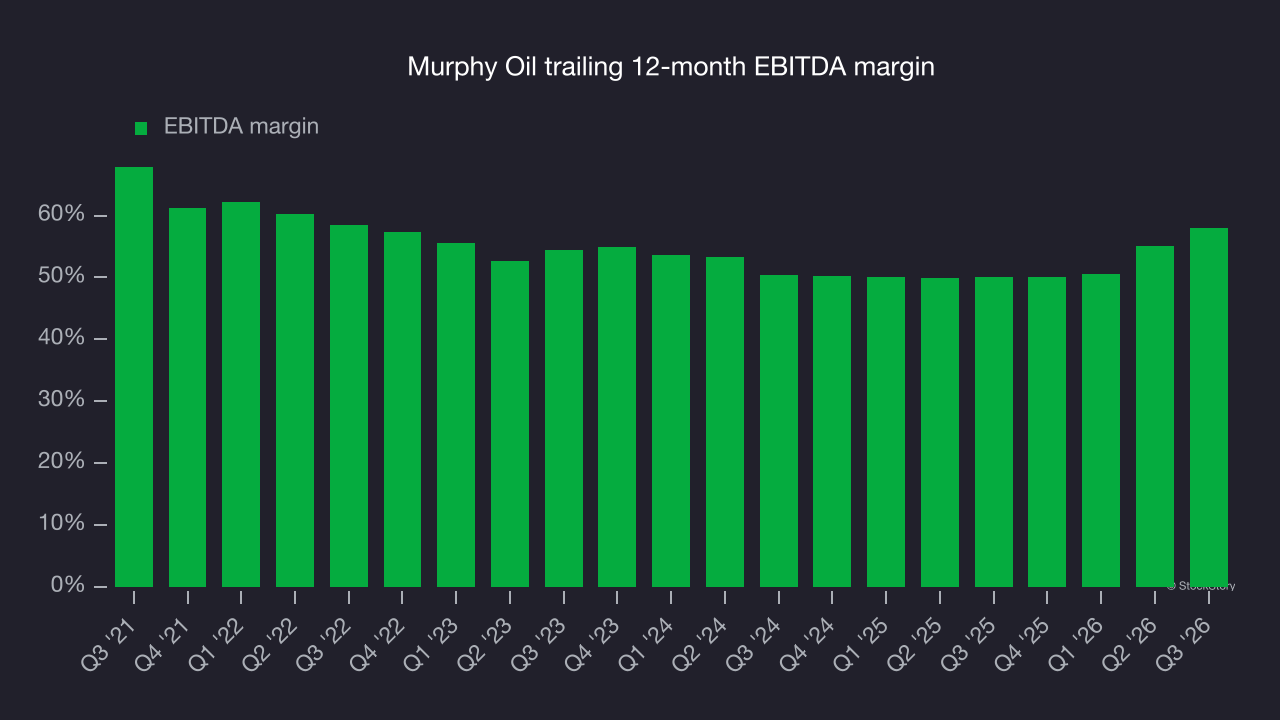
This quarter, Murphy Oil generated an EBITDA margin of 64%, up 10.7 percentage points year on year. The improvement indicates greater efficiency. Its adjusted EBITDA beat Wall Street’s consensus estimates by 8.2%.
Free cash flow
Adjusted EBITDA shows how profitable a company’s existing wells are before financing and reinvestment decisions, but free cash flow shows how much value remains after paying the cost of replacing those wells. In upstream energy, production naturally declines over time, so companies must continuously reinvest just to stand still. A producer can report strong EBITDA margins yet generate little or no free cash flow if its wells decline quickly or if new drilling is expensive. Free cash flow therefore captures not only how efficiently a company produces hydrocarbons today, but also how costly it is to sustain that production into the future.
Murphy Oil has shown strong cash profitability, enabling it to reinvest, return capital to investors and stay ahead of the competition while maintaining an ample cushion. The company’s free cash flow margin was among the best in the energy upstream and integrated energy sector, averaging 19.8% over the last five years.
Absolute free cash flow margin levels matter, but so does stability. All else equal, a steady 25.0% average free cash flow margin across commodity price cycles is preferable to very high margins when times are good and negative ones when they’re tough.
Murphy Oil’s ratio of quarterly free cash flow volatility to West Texas Intermediate, or WTI, crude price volatility over the past five years was 5.4 (lower is better), indicating strong insulation from commodity swings. This stability supports capital access in downturns and positions Murphy Oil to act as a consolidator when weaker peers are forced to retrench.
Why assess stability against commodity prices at the free cash flow line rather than compare revenue or EBITDA with WTI in Murphy Oil’s case? What ultimately matters is not how much revenue or profit a company earns when prices are high but how much cash it can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging effectiveness to growth and maintenance capex to management behavior during good times and bad.
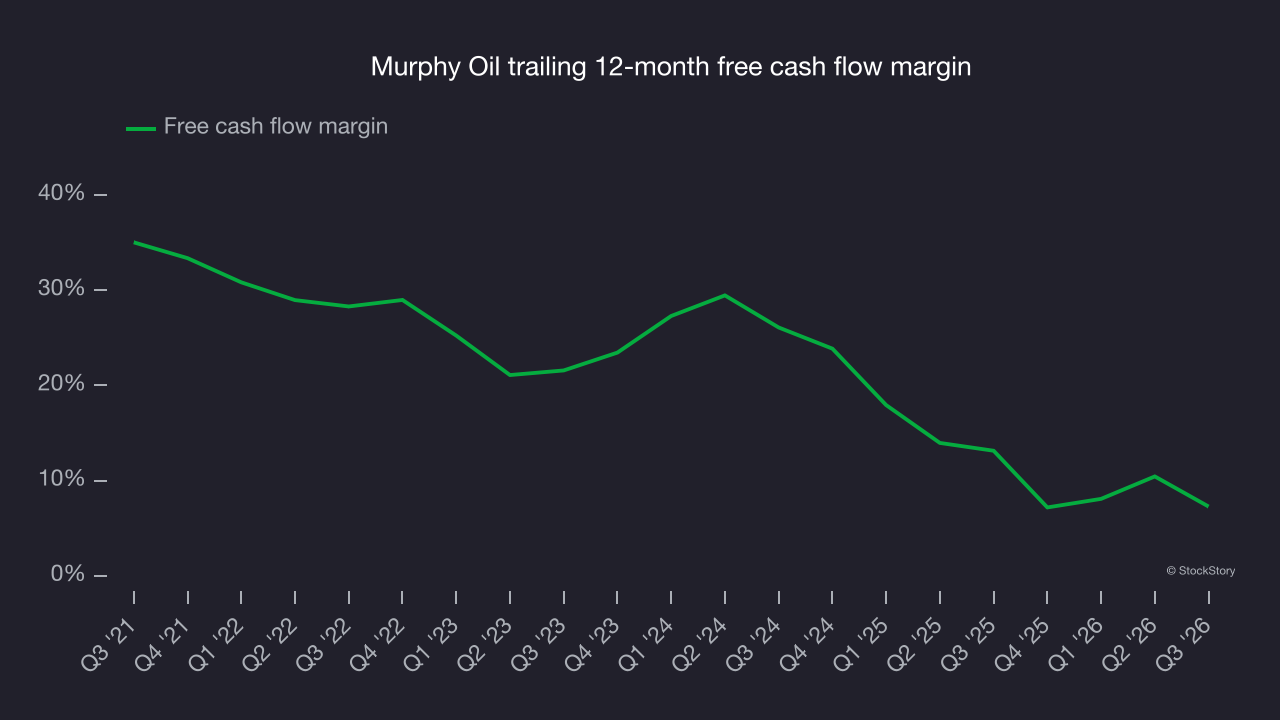
Murphy Oil’s free cash flow came in at $73.64 million in Q3, equivalent to an 8.7% margin. The company’s cash profitability declined as its margin was 13.2 percentage points lower than in the same quarter last year, suggesting its historical struggles have continued.
Key takeaways from Murphy Oil’s Q3 results
Murphy Oil’s wide revenue beat stood out in a solid quarter, with EPS also topping analysts’ consensus estimates. The stock remained flat at $36.27 immediately after the results.
Murphy Oil had a solid quarter, but the broader picture matters when evaluating the stock. The latest quarter is only one part of assessing longer-term business quality. Quality, combined with valuation, can help determine whether the stock is a buy. Read the full research report here for more on Murphy Oil (it’s free).
If you believe this article contains misleading, harmful, or spam content, please let us know.
Report this articleMore News
View More
Recent Quotes
View MoreQuotes delayed at least 20 minutes.
By accessing this page, you agree to the Privacy Policy and Terms Of Service.











