




Financial News
Lumen (NYSE:LUMN) posts Q3 2026 sales in line with estimates

Telecommunications infrastructure company Lumen Technologies (NYSE: LUMN) met Wall Street’s revenue expectations in Q3 2026, but revenue fell by 12.1% year on year to $2.72 billion. Its non-GAAP loss of $0.14 per share was 41% above analysts’ consensus estimates.
For more on Lumen, read our free full research report.
Lumen (LUMN) Q3 2026 highlights:
- Revenue $2.72 billion vs S&P analysts’ consensus estimates of $2.73 billion (12.1% year-on-year decline, in line)
- Adjusted EPS -$0.14 vs S&P analysts’ consensus estimates of -$0.24 (41% beat)
- Adjusted EBITDA $715 million vs analysts’ consensus estimates of $688.3 million (26.3% margin, 3.9% beat)
- EBITDA guidance $3.2 billion at the midpoint for the full year, in line with analysts’ consensus estimates
- Operating margin -6.2%, down from -3.8% in the same quarter last year
- Free cash flow -$354 million, down from $1.66 billion in the same quarter last year
- Market capitalization $4.90 billion
“We’re delivering what we promised and building a stronger, more valuable Lumen,” said Kate Johnson, CEO of Lumen. “AI-driven demand for connectivity is fueling momentum in our Strategic revenue base. Customers are choosing our platform to simplify their networks and get more from every connection. As we modernize our portfolio, we’re strengthening the economics of our business and investing in what comes next.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can deliver a good quarter or two, but many enduring ones grow for years.
With $11.46 billion in revenue over the past 12 months, Lumen is larger than most business services companies and benefits from economies of scale, enabling it to gain more leverage on its fixed costs than smaller competitors. This also gives it the flexibility to offer lower prices. However, its scale is a double-edged sword because it’s challenging to maintain high growth rates when you’ve already captured a large portion of the addressable market. To expand meaningfully, Lumen likely needs to adjust its prices, innovate with new offerings or enter new markets.
Lumen’s demand was weak over the last five years. Its revenue fell by 10.5% annually.
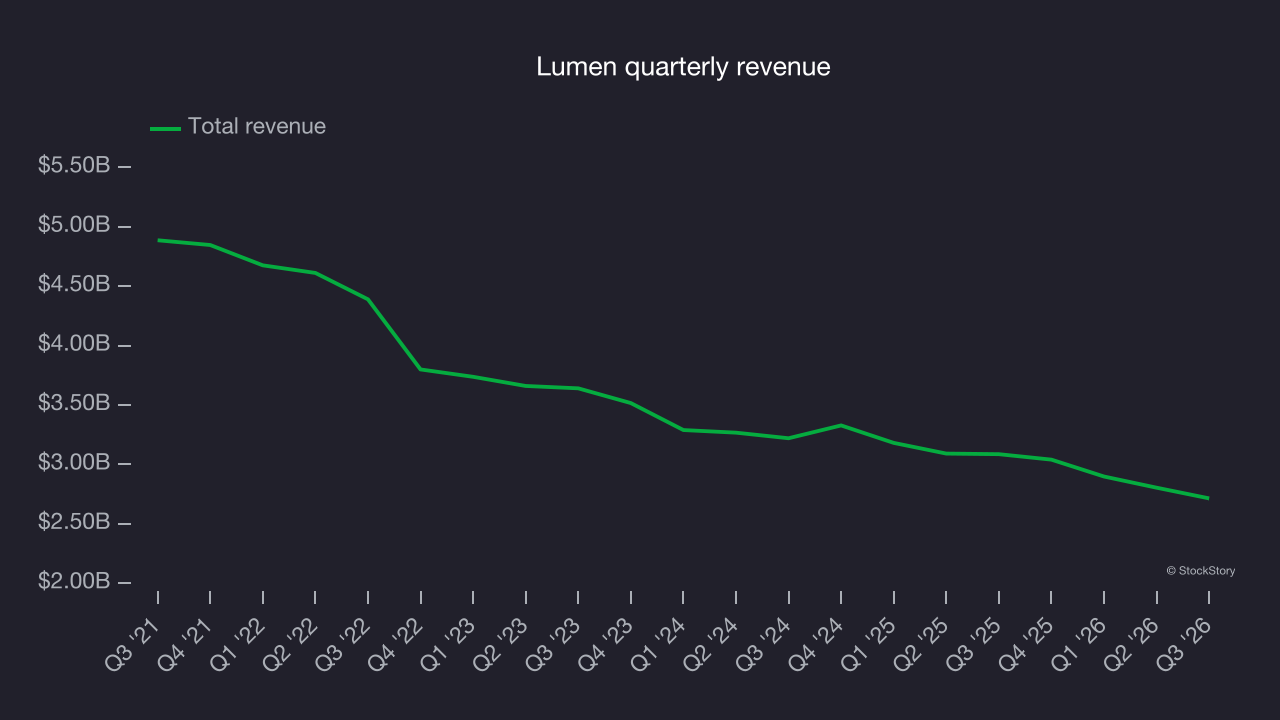
Long-term growth is the most important, but within business services, a half-decade historical view may miss new innovations or demand cycles. Lumen’s annualized revenue declines of 7.2% over the last two years suggest its demand continued shrinking. 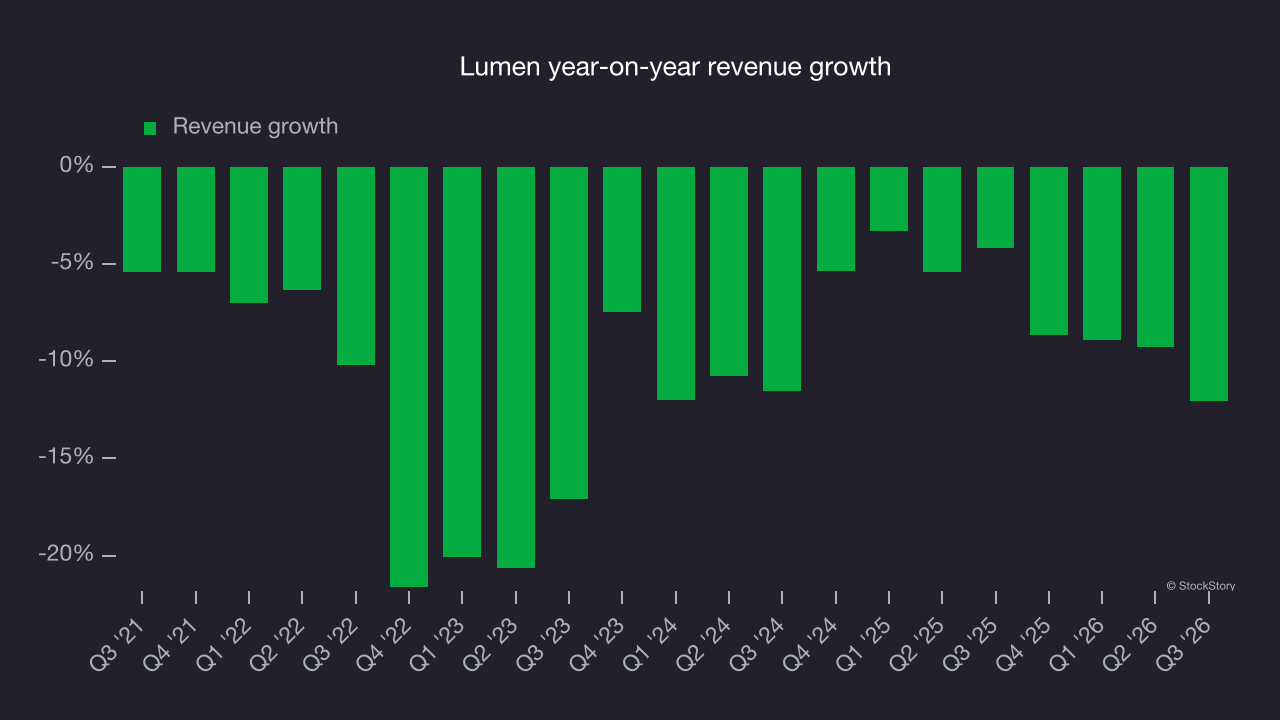
We can better understand the company’s revenue dynamics by analyzing its most important segment, Large Enterprise. Over the last two years, Lumen’s Large Enterprise revenue (services provided to businesses) averaged 3.7% year-on-year declines. This segment has outperformed its total revenue during the same period, lifting the company’s performance. 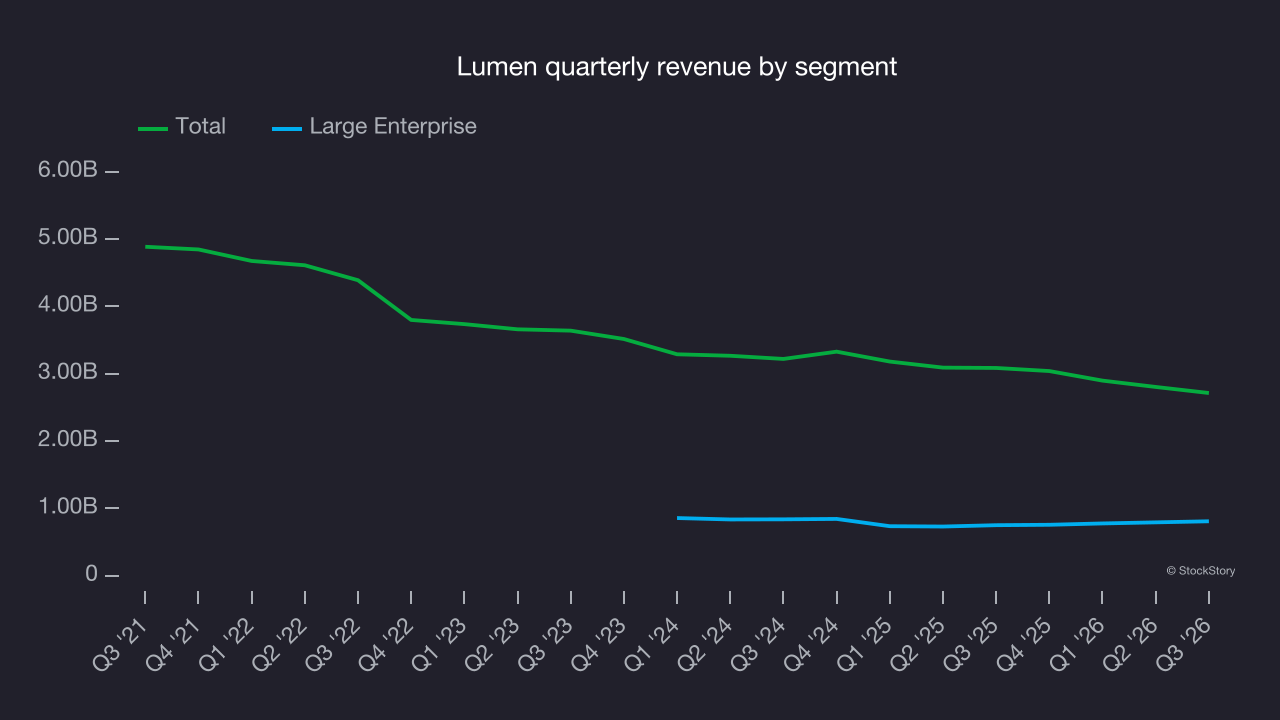
This quarter, Lumen reported an uninspiring 12.1% year-on-year revenue decline to $2.72 billion, in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to decline by 5.9% over the next 12 months, according to S&P, similar to its two-year rate. While this projection is better than its two-year trend, its ongoing demand struggles remain a concern.
Adjusted operating margin
Lumen’s high expenses have contributed to an average adjusted operating margin of negative 11.8% over the last five years. Unprofitable business services companies require extra scrutiny because they could be vulnerable in a downturn. That raises doubts about whether the business can endure a full cycle.
Lumen’s adjusted operating margin decreased by 23.2 percentage points over the last five years. Its performance was poor, showing that costs were rising and it couldn’t pass them on to its customers.
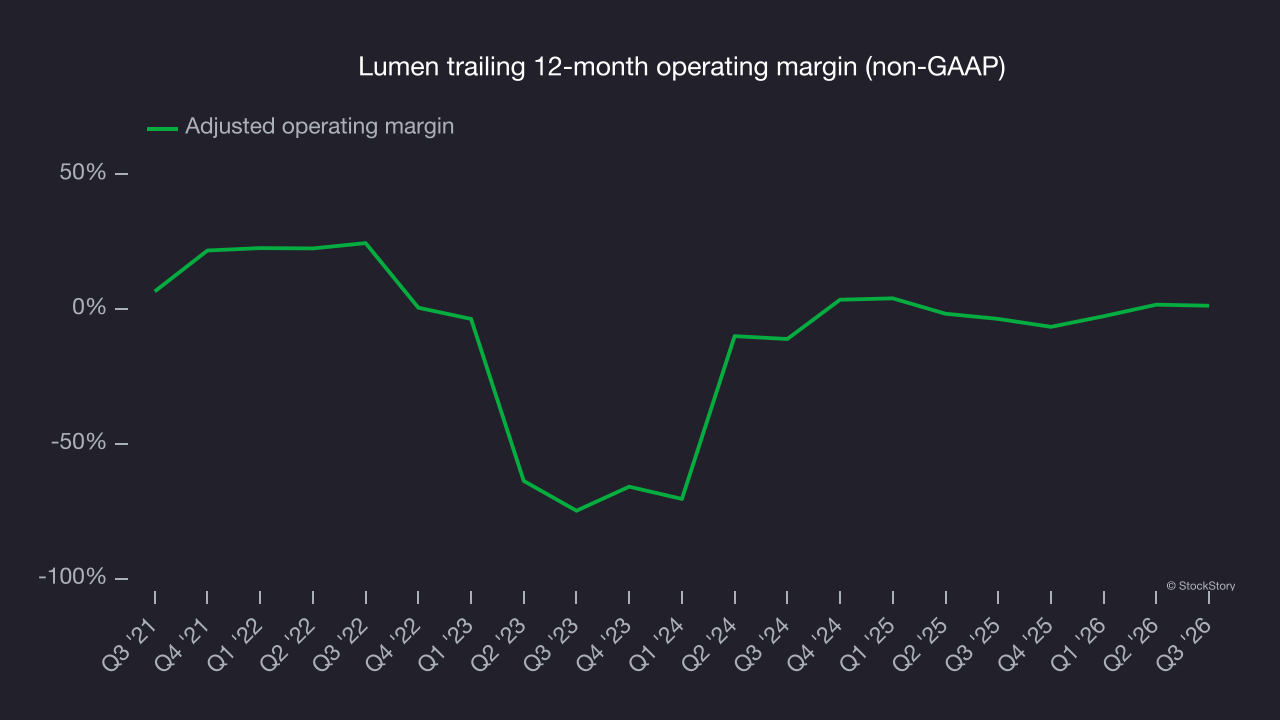
This quarter, Lumen generated a negative 6.2% adjusted operating margin. The company’s persistent lack of profits is a concern.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Lumen’s EPS declined by 17.5% annually over the last five years, more than its revenue. This indicates the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
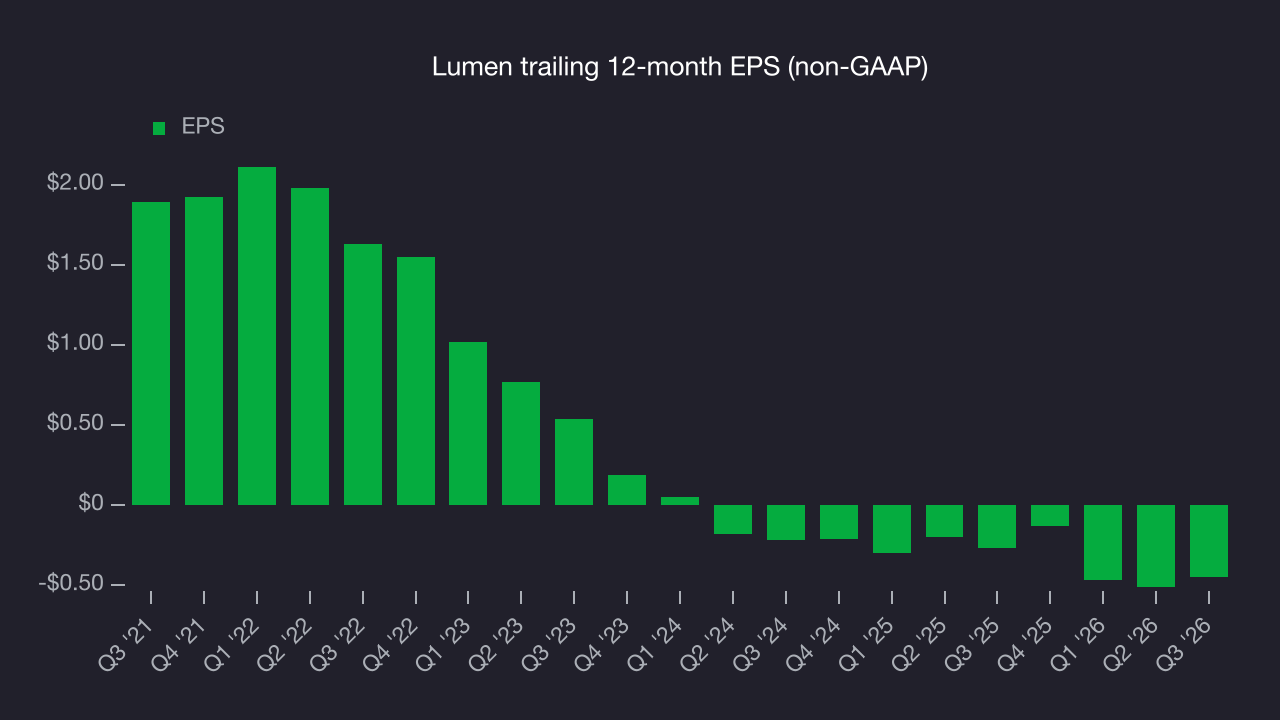
A closer look at Lumen’s earnings helps explain its performance. As mentioned earlier, Lumen’s adjusted operating margin declined by 23.2 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Lumen, its two-year annual EPS declines of 43% show it’s continued to underperform. These results were poor regardless of the period examined.
In Q3, Lumen reported adjusted EPS of negative $0.14, up from negative $0.20 in the same quarter last year. This result beat analysts’ consensus estimates by a wide margin, a positive for shareholders. Over the next 12 months, Wall Street expects Lumen to narrow its losses. Analysts forecast its full-year EPS will improve from negative $0.45 to negative $0.35, according to S&P.
Key takeaways from Lumen’s Q3 results
Lumen’s EPS beat was the highlight of Q3, with revenue coming in line with analysts’ consensus estimates. The quarter was solid overall, with some clear positives. Shares remained flat at $4.50 immediately after the release.
When deciding whether to buy Lumen, consider valuation, business quality and the latest earnings. For more on these factors, read our full research report here (it’s free).
If you believe this article contains misleading, harmful, or spam content, please let us know.
Report this articleMore News
View More
Recent Quotes
View MoreQuotes delayed at least 20 minutes.
By accessing this page, you agree to the Privacy Policy and Terms Of Service.











