




Financial News
Cognex (NASDAQ:CGNX) reports Q3 2026 in line with expectations but stock drops

Machine vision technology company Cognex (NASDAQ: CGNX) met Wall Street’s revenue expectations in Q3 2026, with revenue up 13.2% year on year to $313.4 million. The company expects next quarter’s revenue to be around $280 million, coming in 2.9% above analysts’ consensus estimates. Its non-GAAP profit of $0.53 per share was 2% above analysts’ consensus estimates.
For more on Cognex, read our free full research report.
Cognex (CGNX) Q3 2026 highlights:
- Revenue $313.4 million vs S&P analysts’ consensus estimates of $313 million (13.2% year-on-year growth, in line)
- Adjusted EPS $0.53 vs S&P analysts’ consensus estimates of $0.52 (2% beat)
- Adjusted EBITDA $111.4 million vs analysts’ consensus estimates of $107.2 million (35.5% margin, 3.9% beat)
- Revenue guidance $280 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $272.2 million
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $1.70 at the midpoint, a 2.4% increase
- Operating margin 32.2%, up from 20.9% in the same quarter last year
- Free cash flow margin 33.1%, up from 31.1% in the same quarter last year
- Market capitalization $9.78 billion
"Our third-quarter results reflect strong execution across the business, with record revenue, broad-based growth across most of our major end markets, and continued progress against our strategic objectives," said Matt Moschner, President and CEO. "We believe we are strengthening our leadership in AI-powered machine vision through innovation, expanding our long-term growth opportunity through the announced acquisition of RealSense, and continuing to help position Cognex to benefit from what we see as powerful trends in automation, robotics, and artificial intelligence."
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long haul.
With $1.13 billion in revenue over the past 12 months, Cognex is a small player in the business services space, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and numerous distribution channels.
Cognex’s 2.1% annualized revenue growth over the last five years was sluggish. This shows it failed to generate significant demand.
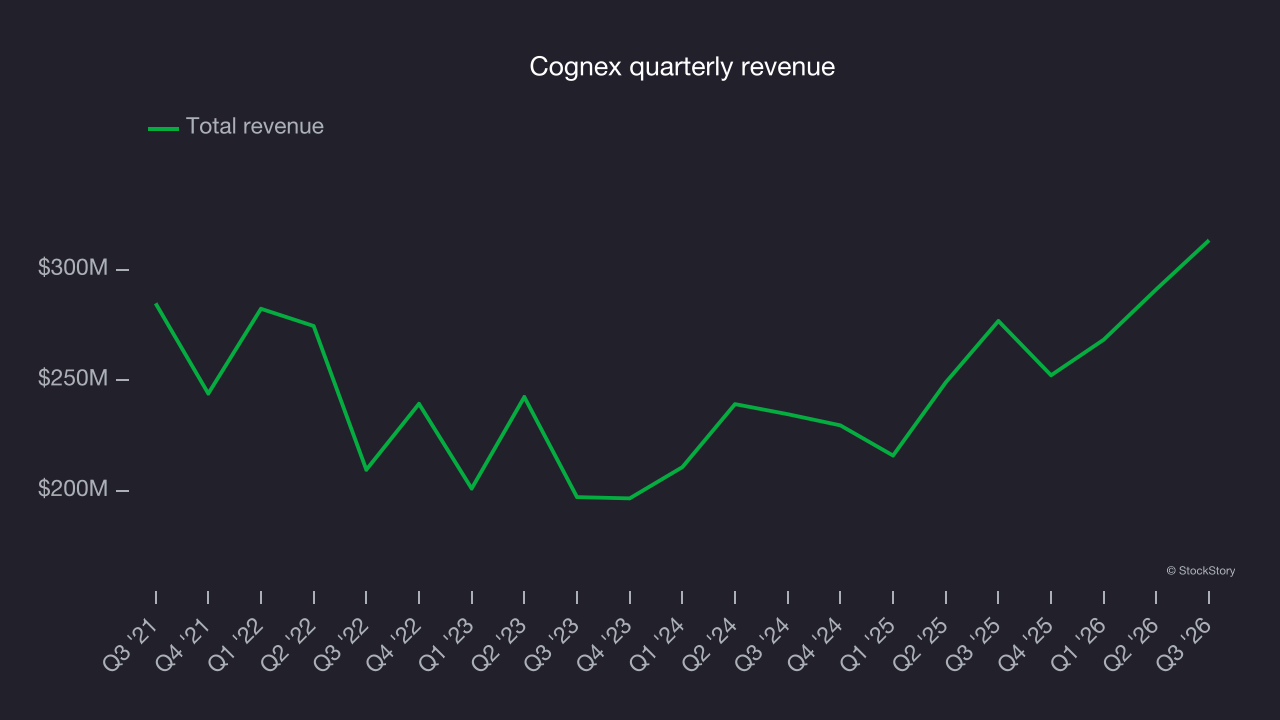
Long-term growth matters most, but within business services, a half-decade historical view may miss recent innovations or disruptive industry trends. Cognex’s annualized revenue growth of 13% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 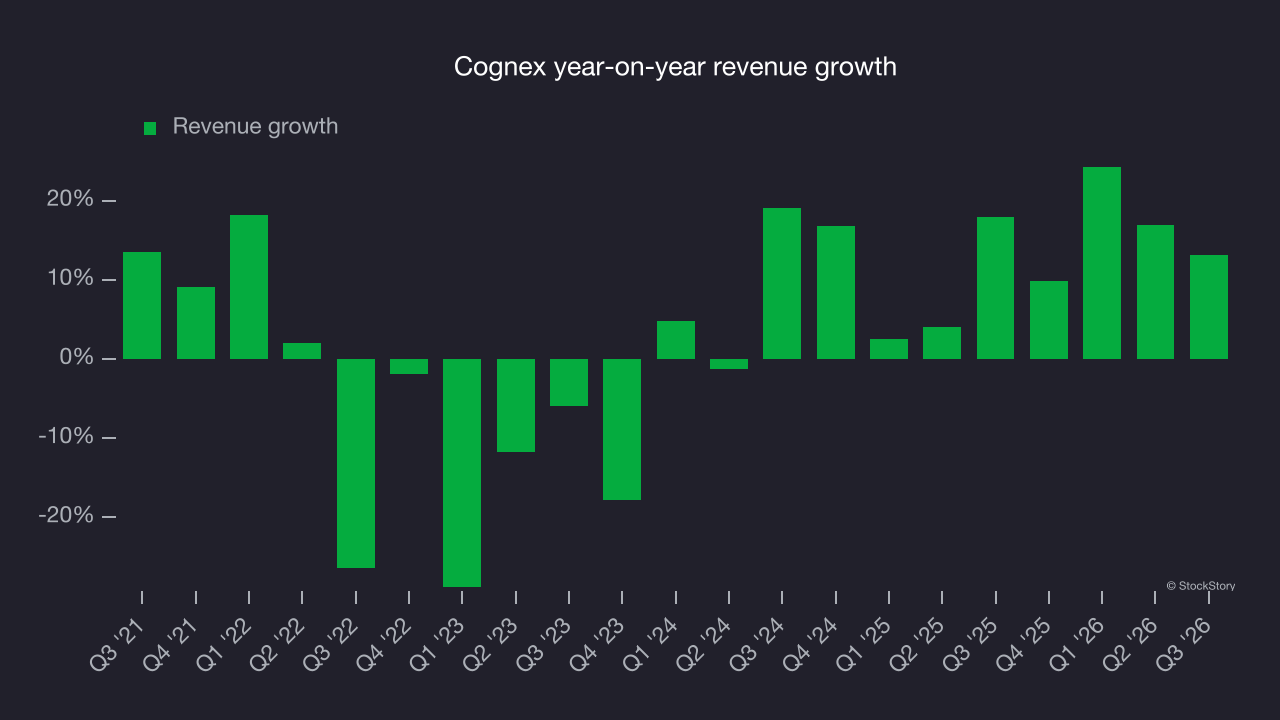
This quarter, Cognex’s year-on-year revenue growth was 13.2%, and its $313.4 million of revenue was in line with Wall Street’s consensus estimates. Management is guiding for an 11% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 8.2% over the next 12 months, according to S&P, a deceleration versus the last two years. Still, this projection is strong and implies the market is forecasting success for its products and services.
Adjusted operating margin
Cognex has performed well over the last five years. It demonstrated high profitability for a business services company, with an average adjusted operating margin of 21.9%.
Cognex’s adjusted operating margin rose by 1.8 percentage points over the last five years, as its revenue growth provided operating leverage.
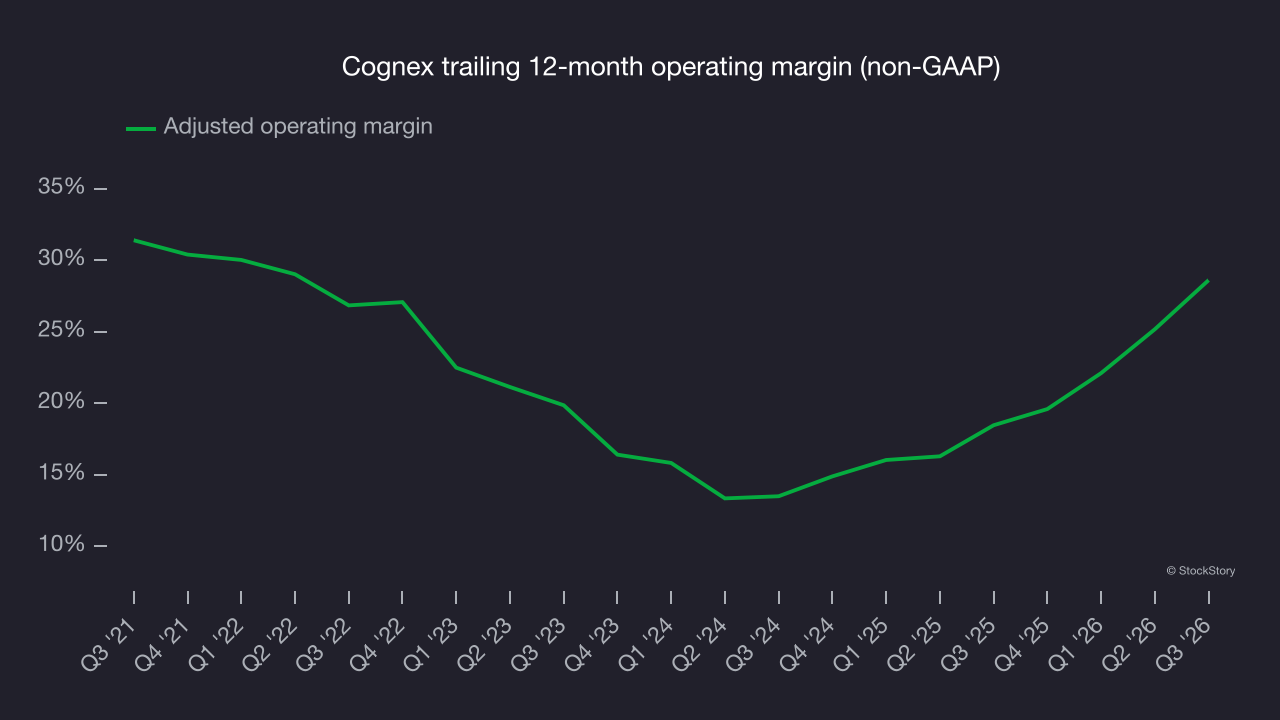
In Q3, Cognex generated an adjusted operating margin of 35.7%, up 12.6 percentage points year on year. This increase was a positive development and shows it operated more efficiently.
Earnings per share
We track the long-term change in earnings per share, or EPS, for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Cognex’s weak 1% annual EPS growth over the last five years aligns with its revenue performance. On the positive side, this indicates its incremental revenue was profitable.
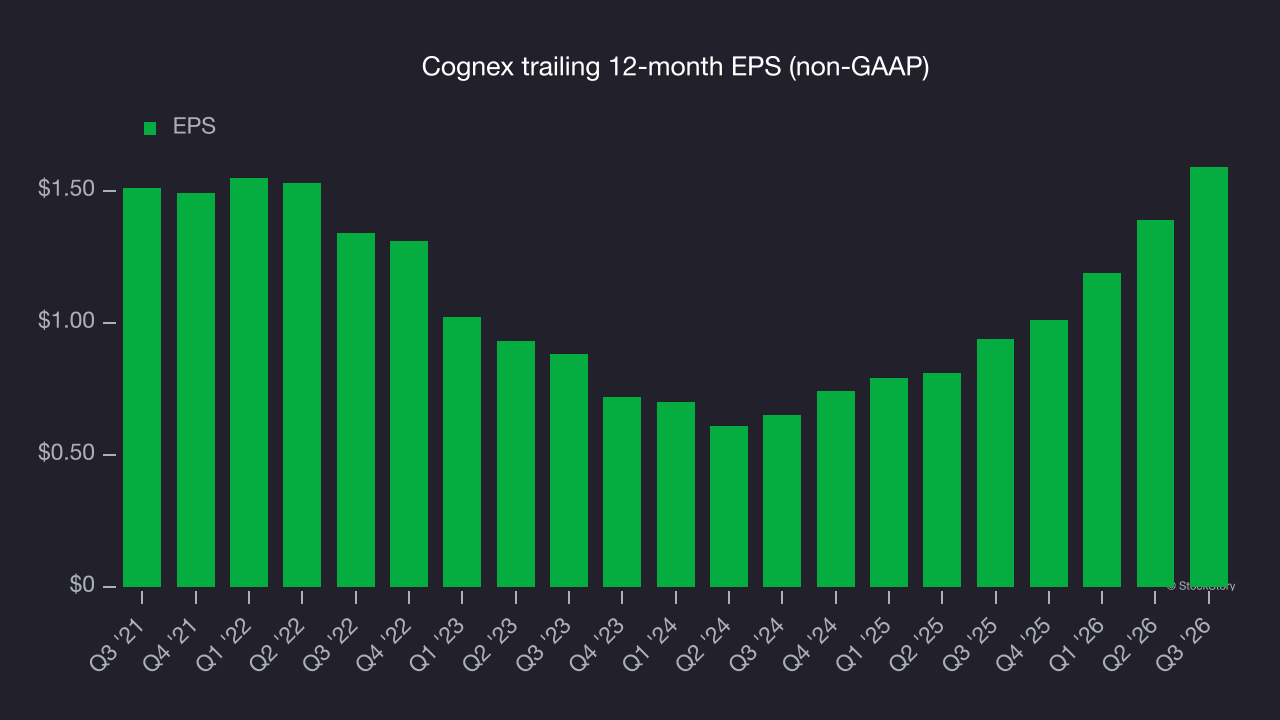
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
Cognex’s two-year annual EPS growth of 56.4% was strong and topped its 13% two-year revenue growth.
We can take a deeper look into Cognex’s earnings quality to better understand the drivers of its performance. Cognex’s adjusted operating margin has expanded over the last two years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
In Q3, Cognex reported adjusted EPS of $0.53, up from $0.33 in the same quarter last year. This result beat analysts’ consensus estimates by 2%. Over the next 12 months, Wall Street expects Cognex’s full-year EPS to grow 21% from $1.59 to $1.92, according to S&P.
Key takeaways from Cognex’s Q3 results
Cognex paired an EPS beat against Wall Street’s consensus with next-quarter revenue guidance well above analysts’ consensus estimates, making this a decent quarter with some clear positives. Investors were likely hoping for more, as shares tumbled 6% to $49.90 immediately after the results.
Cognex’s latest quarter is only one piece of its longer-term business quality picture. Business quality, combined with valuation, can help determine whether the stock is a buy. Read the full research report here (it’s free).
If you believe this article contains misleading, harmful, or spam content, please let us know.
Report this articleMore News
View More
Recent Quotes
View MoreQuotes delayed at least 20 minutes.
By accessing this page, you agree to the Privacy Policy and Terms Of Service.











