




Financial News
Clover Health (NASDAQ:CLOV) posts better-than-expected sales in Q3 2026, full-year outlook slightly exceeds expectations

Health insurance company Clover Health (NASDAQ: CLOV) announced better-than-expected revenue in Q3 2026, with revenue up 52.9% year on year to $759.3 million. The company’s full-year revenue guidance of $2.99 billion at the midpoint came in 1% above analysts’ consensus estimates. Its GAAP profit of $0.01 per share was $0.01 above analysts’ consensus estimates.
For more on Clover Health, read the full research report for free.
Clover Health (CLOV) Q3 2026 highlights:
- Revenue $759.3 million vs S&P analysts’ consensus estimates of $740.3 million (52.9% year-on-year growth, 2.6% beat)
- EPS (GAAP) $0.01 vs analysts’ consensus estimates of $0 ($0.01 beat)
- Adjusted EBITDA $16.05 million vs analysts’ consensus estimates of $10.11 million (2.1% margin, 58.7% beat)
- Revenue guidance The company slightly lifted its revenue guidance for the full year to $2.99 billion at the midpoint from $2.96 billion
- EBITDA guidance $80 million at the midpoint for the full year, in line with analysts’ consensus estimates
- Operating margin 0.8%, up from -4.9% in the same quarter last year
- Free cash flow margin 9.2%, up from 2.3% in the same quarter last year
- Customers 158,907, up from 157,309 in the previous quarter
- Market capitalization $2.28 billion
“Our results further demonstrate our technology-powered differentiation, and how earlier and better care management, market-leading growth, and increasing profitability can reinforce one another under the right model,” said Clover Health CEO Andrew Toy. "Through Clover Assistant, we are committed to delivering better clinical quality and lower total cost of care. We are pleased that this continues to show up in our results, with ~98% of our members enrolled in our 5 Star rated PPO for Payment Year 2028, alongside our third consecutive year of nation-leading HEDIS performance.”
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Clover Health’s 17.8% annualized revenue growth over the last five years was impressive. Its growth surpassed the average healthcare company and shows its offerings resonate with customers.
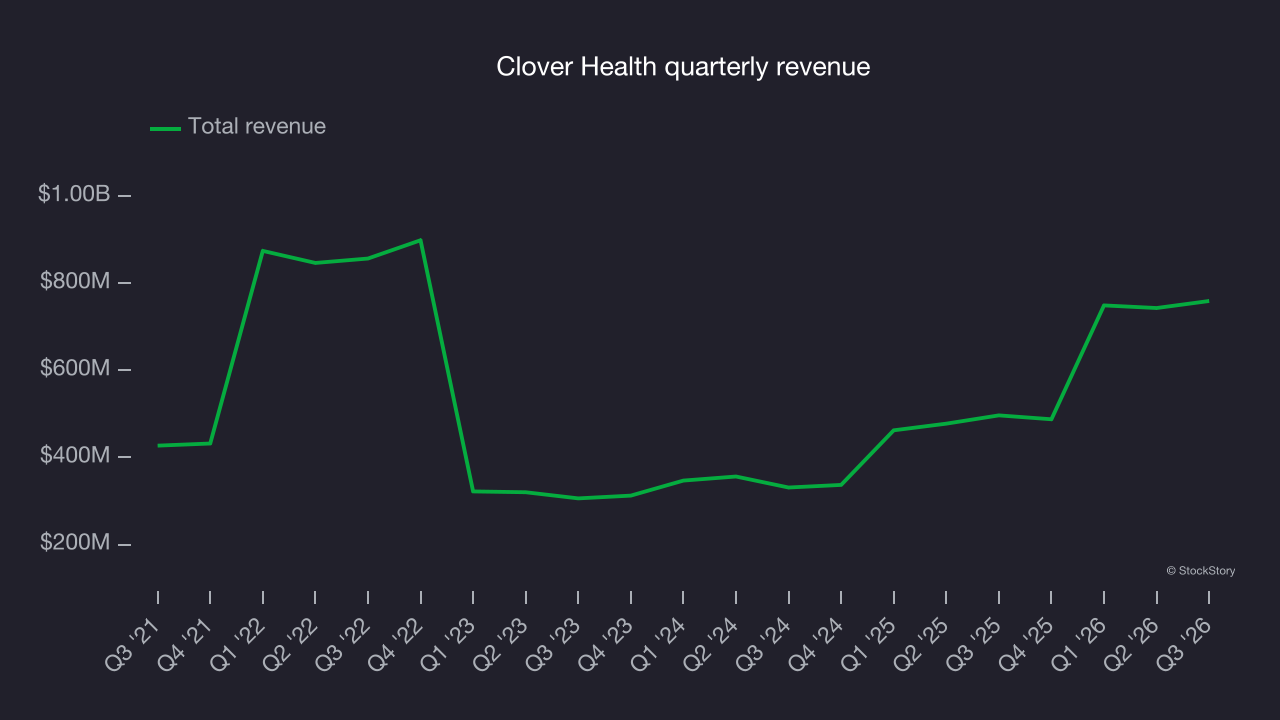
Long-term growth matters most, but within healthcare, a half-decade historical view may miss recent innovations or disruptive industry trends. Clover Health’s annualized revenue growth of 42.6% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 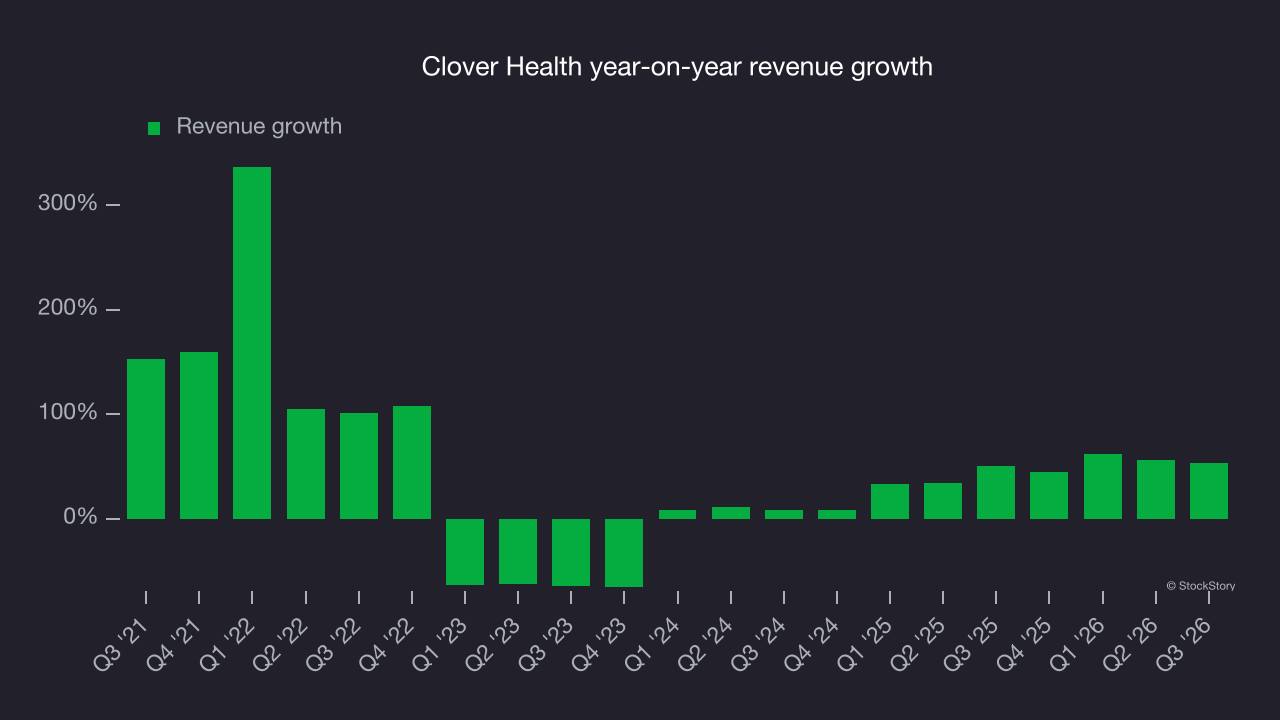
The company’s customer count, which reached 158,907 in the latest quarter, provides further insight into its revenue dynamics. Over the last two years, Clover Health’s customer base averaged 43.3% year-on-year growth. This was in line with revenue growth, indicating that the average customer spent roughly the same amount each year on the company’s products and services. 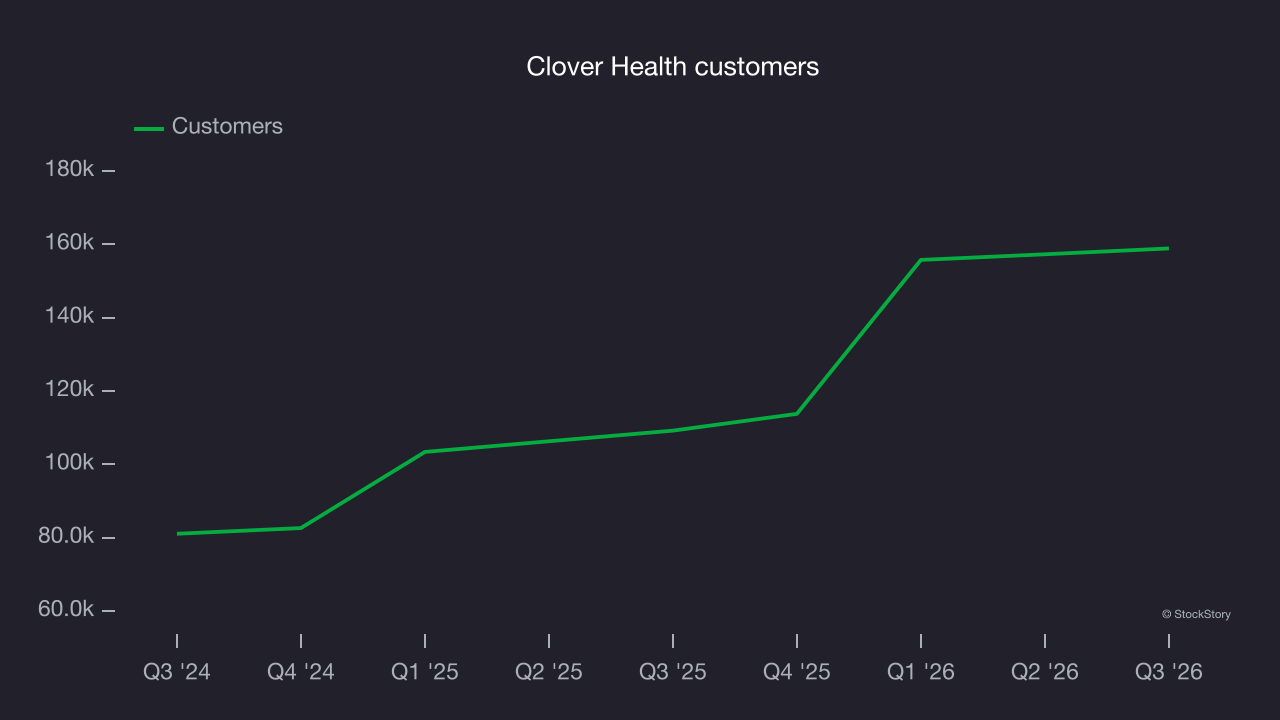
This quarter, Clover Health reported strong year-on-year revenue growth of 52.9%, and its $759.3 million of revenue beat Wall Street’s consensus estimates by 2.6%.
Looking ahead, sell-side analysts expect revenue to grow 23.7% over the next 12 months, according to S&P, a deceleration versus the last two years. Still, this projection is strong and suggests the market expects continued success for its products and services.
Adjusted operating margin
Adjusted operating margin is a key measure of profitability. Think of it as net income (the bottom line) excluding the impact of non-recurring expenses, taxes and interest on debt – metrics less connected to business fundamentals.
Although Clover Health was profitable this quarter from an operational perspective, it’s generally struggled over a longer time period. Its expensive cost structure has contributed to an average adjusted operating margin of negative 7.7% over the last five years. Unprofitable healthcare companies warrant closer scrutiny because their vulnerabilities can become apparent in a downturn.
On the positive side, Clover Health’s adjusted operating margin rose by 15.7 percentage points over the last five years, as its revenue growth provided operating leverage. More recently, that trajectory has continued, with its margin increasing by 7.2 percentage points over two years. These gains are a positive sign and show continued momentum.
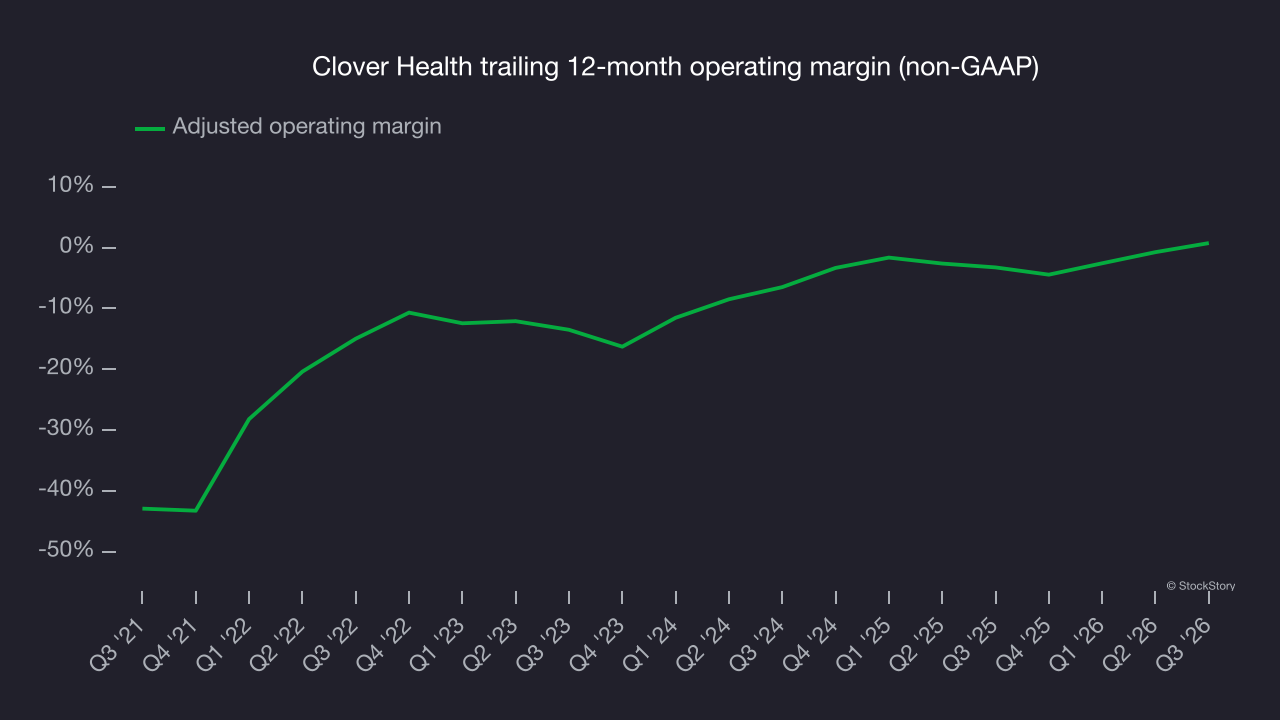
In Q3, Clover Health generated an adjusted operating margin of 1.9%, up 6.8 percentage points year on year. This increase was a positive development and shows it was more efficient.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Clover Health’s full-year EPS flipped from negative to positive over the last five years. This is a good sign and shows it’s at an inflection point.
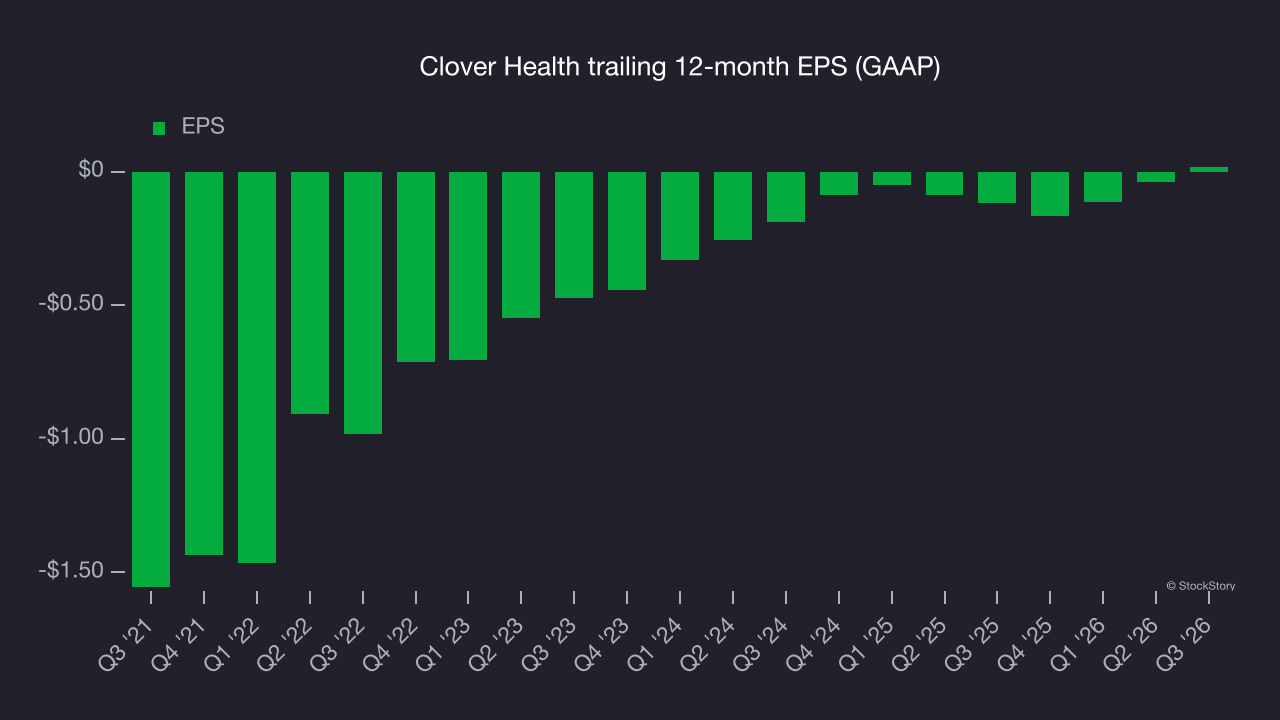
In Q3, Clover Health reported EPS of $0.01, up from negative $0.05 in the same quarter last year. The result beat analysts’ consensus estimates by a wide margin, a positive outcome for shareholders. Over the next 12 months, Wall Street expects Clover Health’s full-year EPS to grow 356% from $0.02 to $0.08, according to S&P.
Key takeaways from Clover Health’s Q3 results
Clover Health topped expectations on both earnings per share and revenue in Q3, making this a decent quarter with some key metrics ahead of analysts’ consensus estimates. Shares remained flat at $4.67 immediately after the results.
When assessing Clover Health as an investment, the latest quarter is only one part of its longer-term business quality. Quality, combined with valuation, can help determine whether the stock is a buy. Read the full research report here (it’s free).
If you believe this article contains misleading, harmful, or spam content, please let us know.
Report this articleMore News
View More
Recent Quotes
View MoreQuotes delayed at least 20 minutes.
By accessing this page, you agree to the Privacy Policy and Terms Of Service.











