




Financial News
Aflac (NYSE:AFL) misses Q3 2026 revenue estimates

Supplemental insurance provider Aflac (NYSE: AFL) missed Wall Street’s revenue expectations in Q3 2026, with revenue falling 25.8% year on year to $3.27 billion. Its non-GAAP profit of $2.43 per share was 35.2% above analysts’ consensus estimates.
For more on Aflac, read our free full research report.
Aflac (AFL) Q3 2026 highlights:
- Revenue $3.27 billion vs S&P analysts’ consensus estimates of $4.22 billion (25.8% year-on-year decline, 22.4% miss)
- Pre-tax profit $500 million (15.3% margin)
- Adjusted EPS $2.43 vs S&P analysts’ consensus estimates of $1.80 (35.2% beat)
- Book value per share $59.08 vs analysts’ consensus estimates of $55.22 (8.3% year-on-year growth, 7% beat)
- Market capitalization $62.19 billion
"We remain focused on more profitable growth and the tactical, opportunistic deployment of capital. We treasure our 2026 milestone of 44 consecutive years of dividend increases. We continue to deploy our balanced approach of investing in growth and driving long-term value while being there for our policyholders when they need us most."
Revenue growth
Insurance companies earn revenue from three primary sources: 1) the core insurance business itself, often called underwriting and represented in the income statement as premiums; 2) income from investing the “float” (premiums collected upfront not yet paid out as claims) in assets such as fixed-income assets and equities; 3) fees from various sources such as policy administration, annuities or other value-added services. Aflac struggled to consistently generate demand over the last five years as its revenue dropped at a 6.2% annual rate. This was below our standards and suggests it’s a low-quality business.
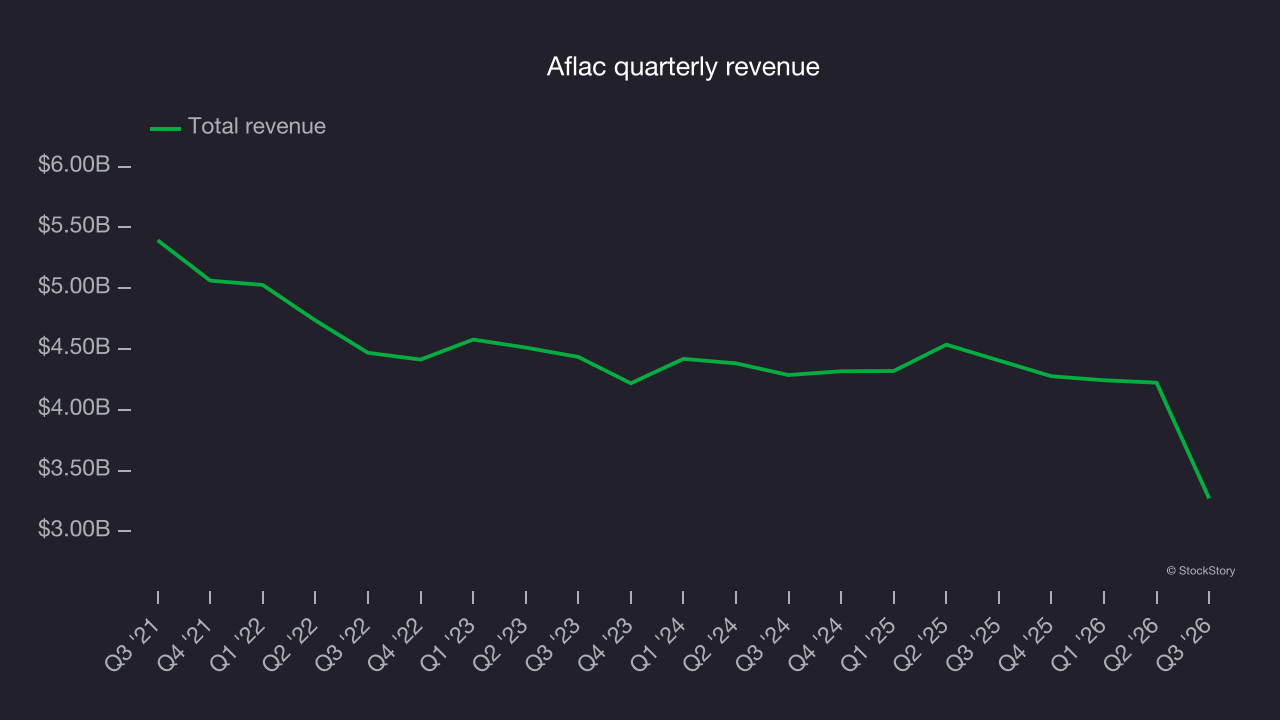
Long-term growth matters most, but within financials, a half-decade historical view may miss recent interest rate changes, market returns and industry trends. Aflac’s annualized revenue declines of 3.8% over the last two years suggest its demand continued shrinking. 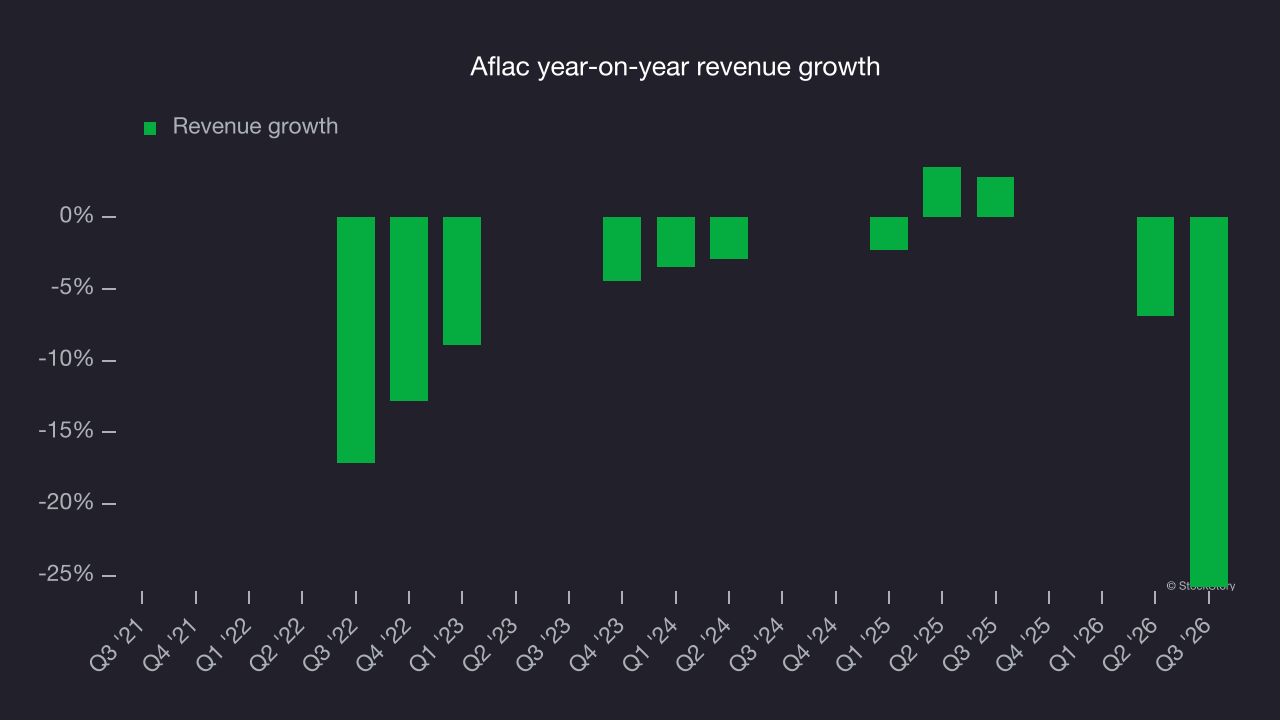 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Aflac missed Wall Street’s consensus estimates and reported an uninspiring 25.8% year-on-year revenue decline, generating $3.27 billion of revenue.
Net premiums earned made up 78.7% of the company’s total revenue during the last five years, meaning insurance operations are Aflac’s largest source of revenue.
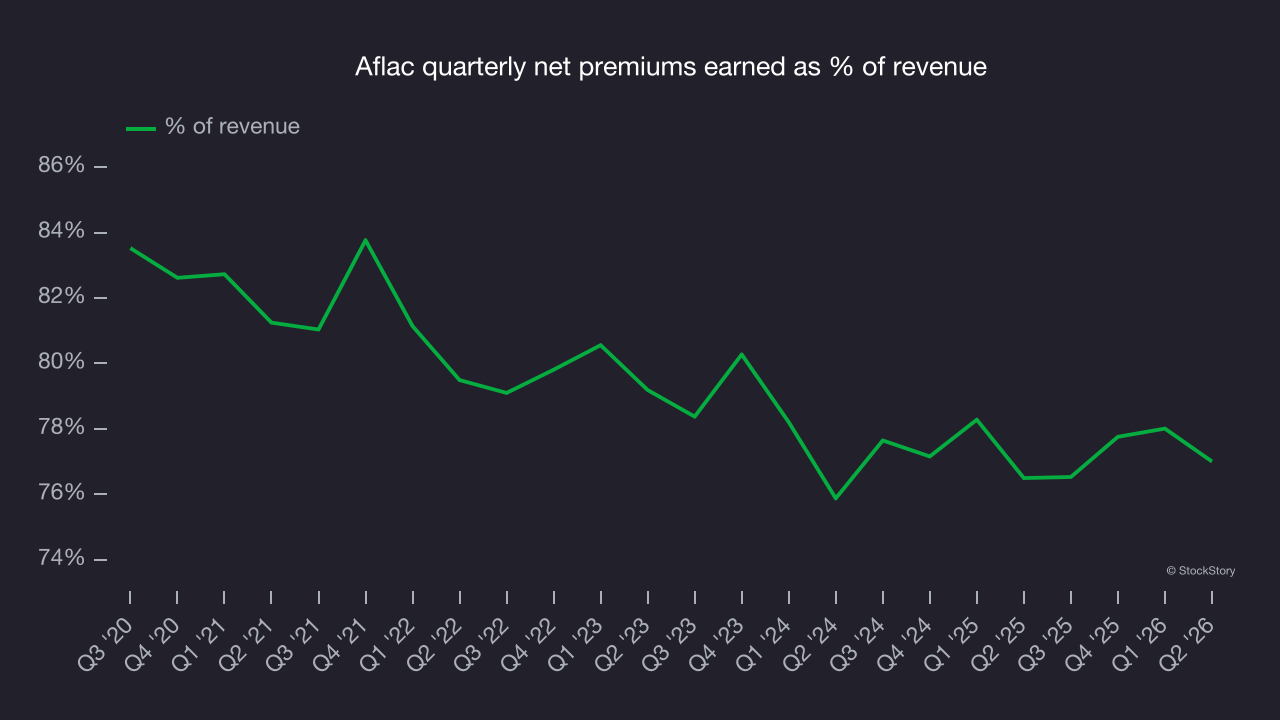
While insurers generate revenue from multiple sources, investors view net premiums earned as the cornerstone – their direct link to core operations stands in sharp contrast to the unpredictability of investment returns and fees.
Book value per share (BVPS)
Insurers are balance sheet businesses, collecting premiums upfront and paying out claims over time. Premiums collected but not yet paid out, often referred to as the float, are invested and create an asset base supported by a liability structure. Book value per share, or BVPS, captures this dynamic by measuring these assets (investment portfolio, cash, reinsurance recoverables) less liabilities (claim reserves, debt, future policy benefits). BVPS is essentially the residual value for shareholders.
BVPS is therefore an important metric for tracking insurers and assessing business quality. While better-known per-share metrics such as earnings per share can sometimes be lumpy due to reserve releases or one-time items and can be managed or skewed while still following accounting rules, BVPS reflects long-term capital growth and is harder to manipulate.
Aflac’s BVPS grew at a sluggish 3.1% annual rate over the last five years. However, BVPS growth has accelerated recently, rising by 15.1% annually over the last two years from $44.60 to $59.08 per share.
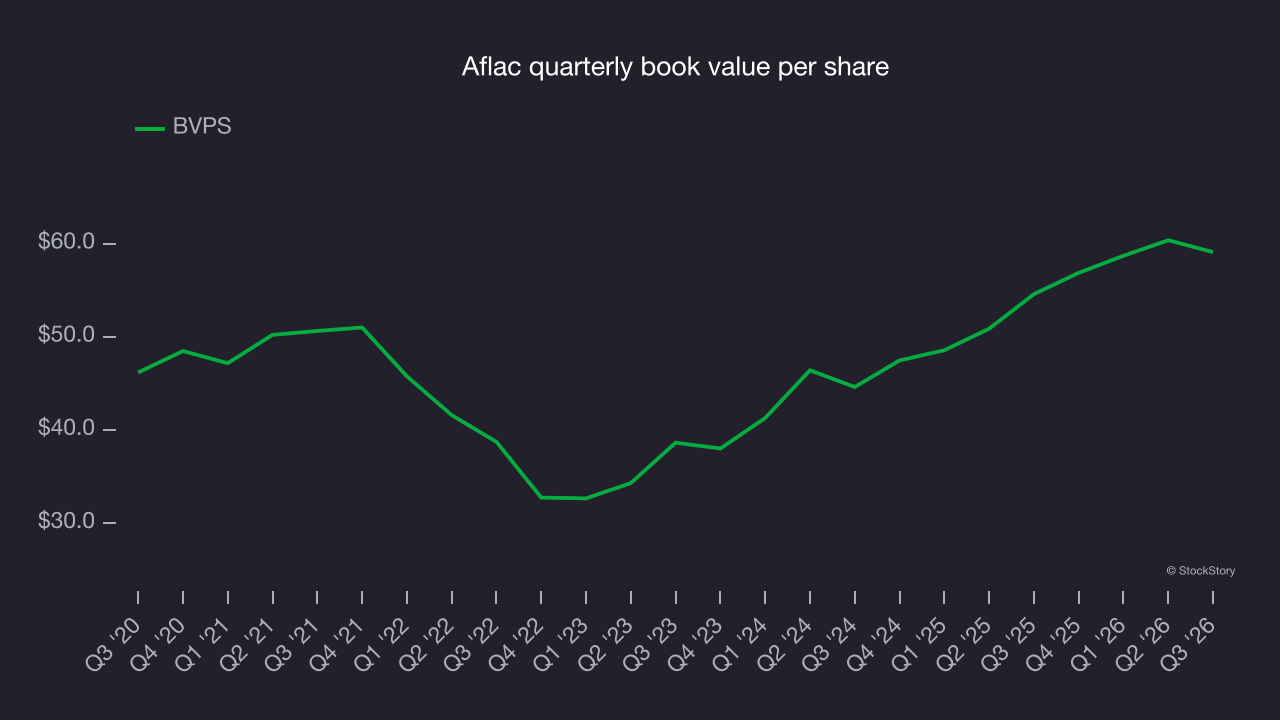
Over the next 12 months, consensus estimates call for Aflac’s BVPS to shrink by 5.1% to $55.22, an unfavorable outlook.
Key takeaways from Aflac’s Q3 results
Aflac delivered a solid Q3, with book value per share well above analysts’ consensus estimates and EPS also topping Wall Street’s consensus. Revenue was the weak spot, missing expectations. Shares remained flat at $125.43 immediately after the results.
When evaluating Aflac as an investment, consider its valuation, business quality and latest quarterly results. Read the full research report here (it’s free).
If you believe this article contains misleading, harmful, or spam content, please let us know.
Report this articleMore News
View More
Recent Quotes
View MoreQuotes delayed at least 20 minutes.
By accessing this page, you agree to the Privacy Policy and Terms Of Service.











