




Financial News
Graphic Packaging Holding’s (NYSE:GPK) Q3 2026: beats on revenue

Consumer packaging solutions provider Graphic Packaging Holding (NYSE: GPK) announced better-than-expected revenue in Q3 2026, but revenue was flat year on year at $2.19 billion. The company expects the full year’s revenue to be around $8.6 billion, close to analysts’ consensus estimates. Its non-GAAP profit of $0.23 per share was 5.6% above analysts’ consensus estimates.
For more on Graphic Packaging Holding, read our free full research report.
Graphic Packaging Holding (GPK) Q3 2026 highlights:
- Revenue $2.19 billion vs S&P analysts’ consensus estimates of $2.15 billion (flat year on year, 1.7% beat)
- Adjusted EPS $0.23 vs S&P analysts’ consensus estimates of $0.22 (5.6% beat)
- Adjusted EBITDA $289 million vs analysts’ consensus estimates of $282.7 million (13.2% margin, 2.2% beat)
- Revenue guidance The company lifted its revenue guidance for the full year to $8.6 billion at the midpoint from $8.5 billion, a 1.2% increase
- Adjusted EPS guidance Management lowered its full-year adjusted EPS guidance to $0.65 at the midpoint, a 16.1% decrease
- EBITDA guidance $1.05 billion at the midpoint for the full year, in line with analysts’ consensus expectations
- Operating margin 4.6%, down from 10.7% in the same quarter last year
- Free cash flow $186 million, up from -$40 million in the same quarter last year
- Market capitalization $2.76 billion
President and CEO Robbert Rietbroek commented, "In the third quarter, we demonstrated progress on our near-term strategic priorities. We drove year-over-year revenue and volume growth and for the second consecutive quarter, expanded Adjusted EBITDA margin sequentially. Our strong relative performance despite elevated inflation reflects the resilience of our business and the benefits of our structural cost reduction and productivity initiatives. Importantly, these actions have created positive operating leverage and better position us to capture benefits from our commercial excellence initiatives and price improvements in the fourth quarter and into 2027. Our decisive actions to enhance and optimize the business this year support continued margin improvement, strong cash flow generation, and a return to EBITDA growth next year."
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Graphic Packaging Holding grew its revenue at a tepid 4.8% compounded annual growth rate, falling short of the industrials sector standard.
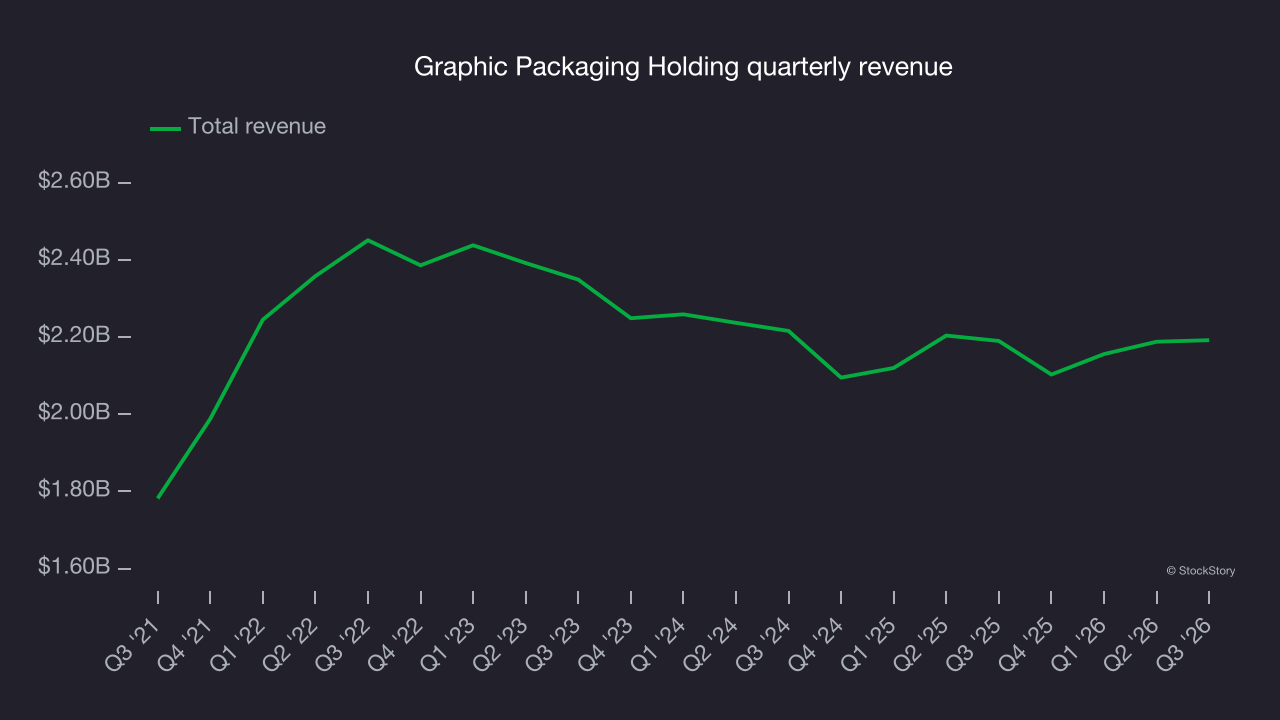
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Graphic Packaging Holding’s performance shows it grew in the past but relinquished its gains over the last two years, as its revenue fell by 1.8% annually. 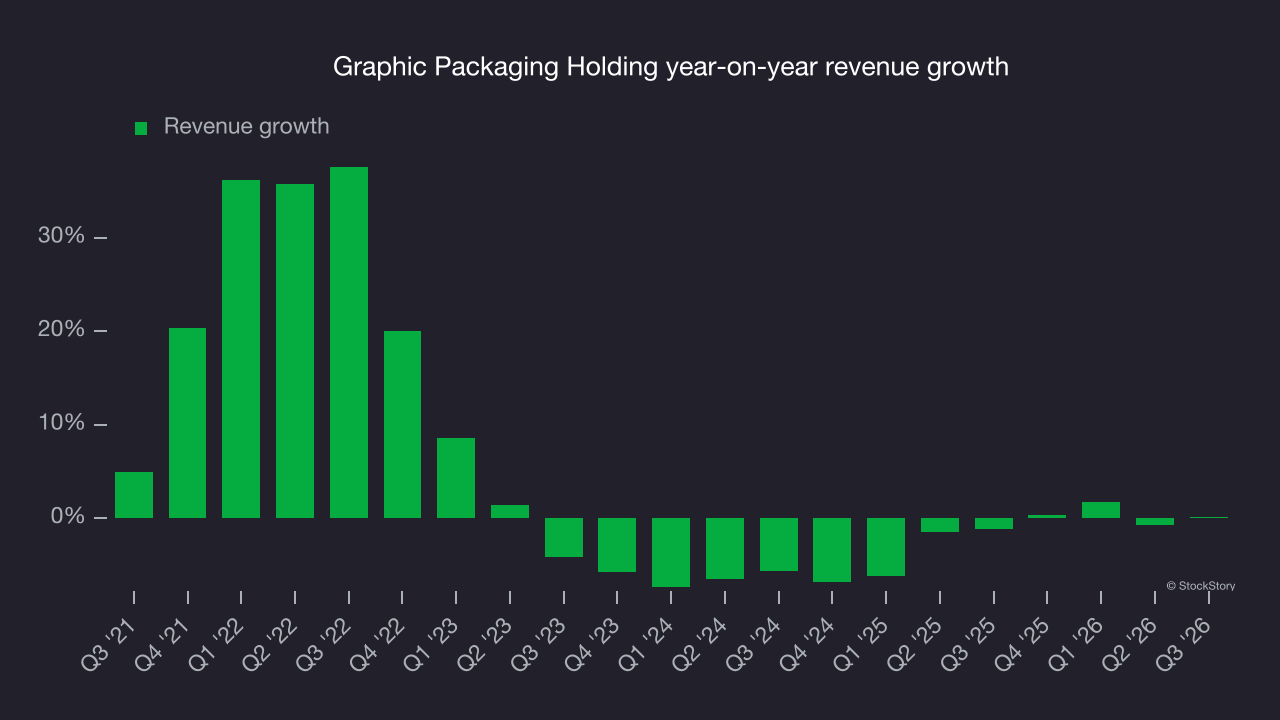
This quarter, Graphic Packaging Holding’s $2.19 billion of revenue was flat year on year but beat Wall Street’s consensus estimates by 1.7%.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months, according to S&P. Although this projection suggests its newer products and services will fuel better top-line performance, it is still below the sector average.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income – the bottom line – excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Graphic Packaging Holding has done a decent job managing its cost base over the last five years. The company has produced an average operating margin of 9.6%, higher than the broader industrials sector.
Analyzing the trend in its profitability, Graphic Packaging Holding’s operating margin decreased by 3.7 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
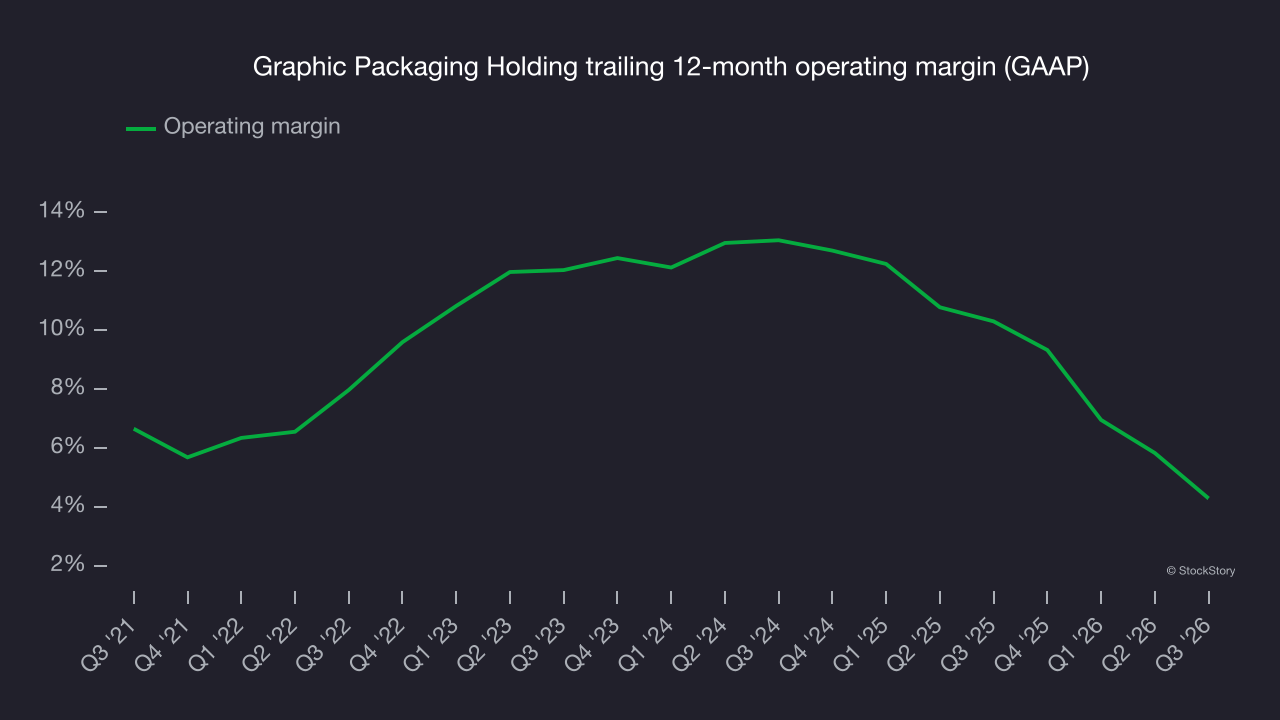
This quarter, Graphic Packaging Holding generated an operating margin of 4.6%, down 6.1 percentage points year on year. The larger decline in operating margin than in gross margin suggests the company was less efficient because expenses such as marketing, R&D and administrative overhead increased.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth – for example, a company could inflate its revenue through excessive spending on advertising and promotions.
Graphic Packaging Holding’s EPS declined by 7.5% annually over the last five years while its revenue grew by 4.8%. This indicates that the company became less profitable on a per-share basis as it expanded due to non-fundamental factors such as interest expenses and taxes.
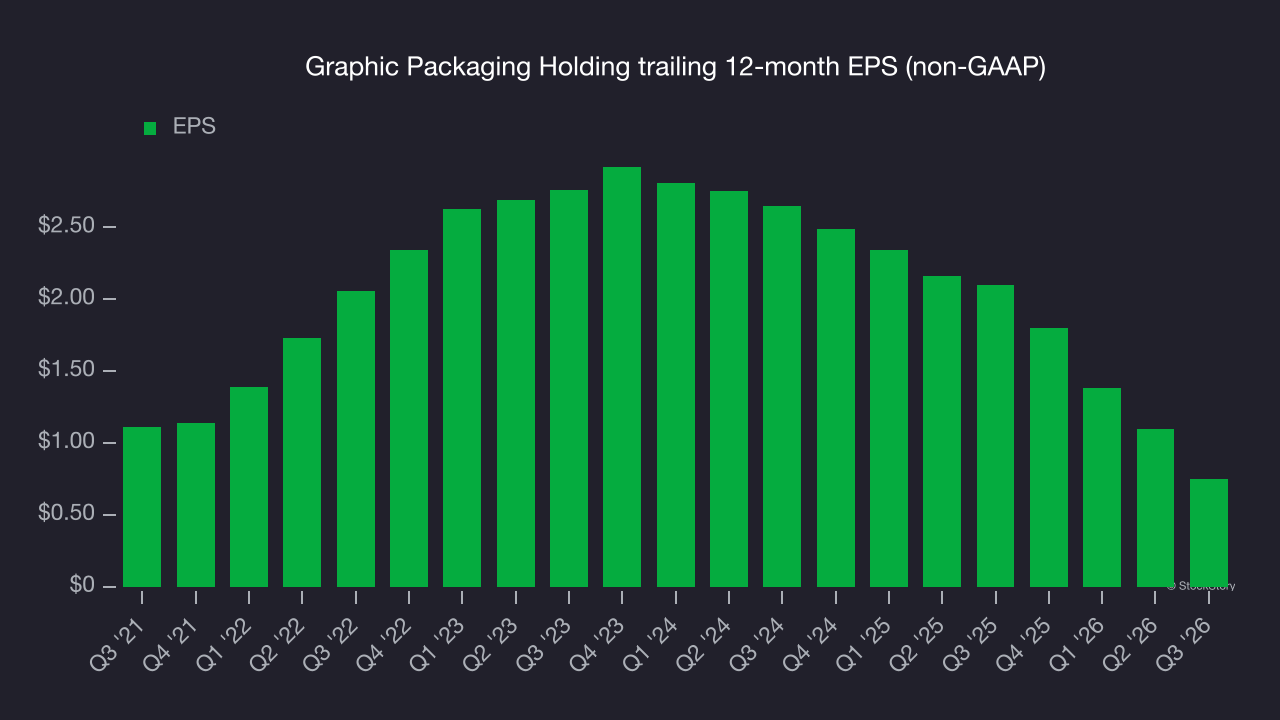
A closer look at Graphic Packaging Holding’s earnings helps explain its performance. As noted earlier, Graphic Packaging Holding’s operating margin declined by 3.7 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
As with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Graphic Packaging Holding, its two-year annual EPS declines of 46.8% show it’s continued to underperform. These results were poor by any measure.
In Q3, Graphic Packaging Holding reported adjusted EPS of $0.23, down from $0.58 in the same quarter last year. Despite falling year on year, this result beat analysts’ consensus estimates by 5.6%. Over the next 12 months, Wall Street expects Graphic Packaging Holding’s full-year EPS to grow 21.5% from $0.75 to $0.91, according to S&P.
Key takeaways from Graphic Packaging Holding’s Q3 results
Graphic Packaging Holding delivered some key positives in Q3, with revenue and EBITDA both topping analysts’ consensus estimates. Full-year revenue guidance, however, offered no upside to expectations, coming in line with consensus. Shares rose 3.7% to $9.69 immediately after the report.
When assessing Graphic Packaging Holding as an investment, the latest quarter matters, but longer-term fundamentals and valuation carry more weight. For more on these factors, read our free full research report here.
If you believe this article contains misleading, harmful, or spam content, please let us know.
Report this articleMore News
View More
Recent Quotes
View MoreQuotes delayed at least 20 minutes.
By accessing this page, you agree to the Privacy Policy and Terms Of Service.











