
Financial News
Team Hinman Issues Reverse Mortgage for Seniors Counseling Update
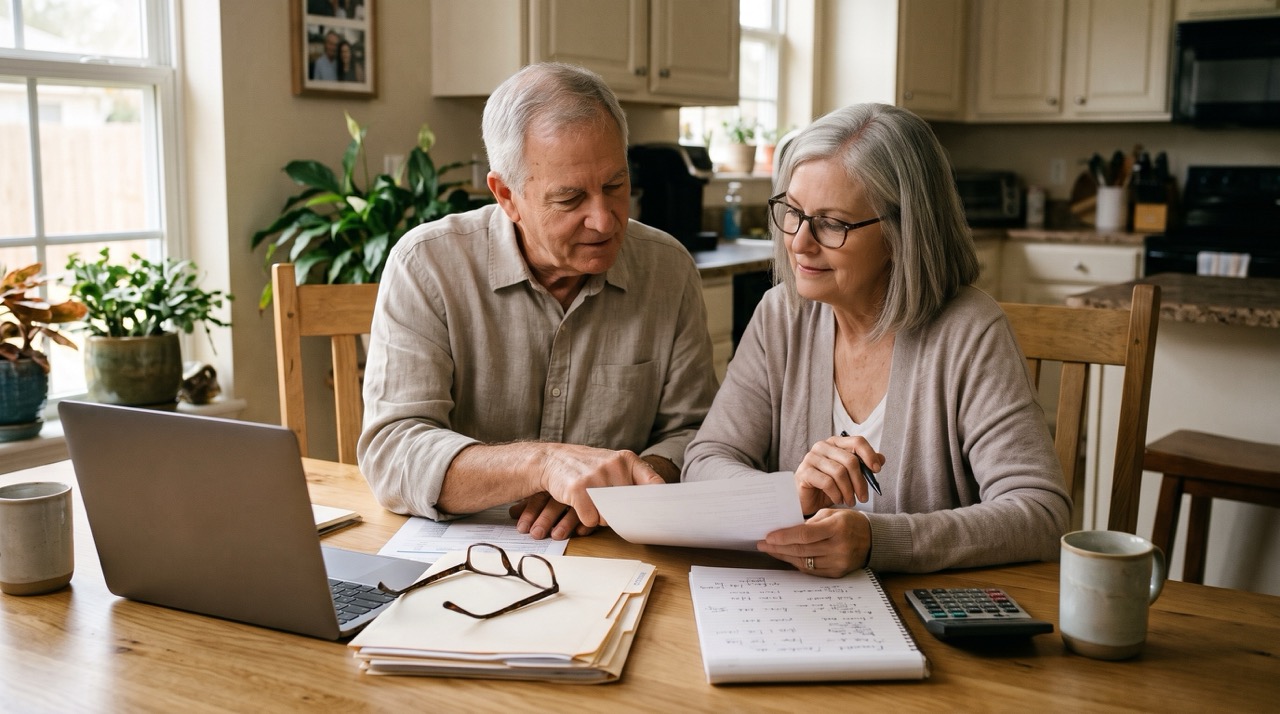 Team Hinman, the residential mortgage practice led by Jamie Hinman, announced today that it is advising homeowners age 62 and older to begin their federally required reverse mortgage counseling earlier in the process. The update follows a proposal to rescind most federal funding for HUD's Housing Counseling Assistance program, which supports the independent counseling every borrower must complete before closing a government-insured reverse mortgage.
On September 25, 2026, the administration proposed rescinding about $810 million in previously approved federal spending. According to HECMWorld.com, the package includes $56.1 million for HUD's Housing Counseling Assistance program, nearly all of the roughly $58 million appropriated for housing counseling in fiscal year 2025. In September, the Government Accountability Office concluded that the Impoundment Control Act does not allow appropriated funds to be withheld past their expiration date without congressional approval. A federal judge has also temporarily suspended a September 30 deadline affecting the disputed funds while litigation continues.
On November 2, the National Reverse Mortgage Lenders Association asked the leaders of the House and Senate Appropriations Committees to restore the funding. In the association's letter, President Steve Irwin warned that without it, "the mandatory, independent counseling that the statute requires is placed at risk."
Section 255 of the National Housing Act requires every prospective borrower in the Home Equity Conversion Mortgage program, known as HECM, to complete a session with an independent, HUD-approved counseling agency. The session covers loan terms, costs, ongoing obligations, and alternatives. Lenders cannot process an HECM application until counseling is complete, so less counseling capacity could mean longer timelines for eligible homeowners.
"Counseling is the first formal step for any homeowner considering a reverse mortgage, and it cannot be skipped," said Jamie Hinman, residential mortgage specialist and leader of Team Hinman. "Given the uncertainty around funding, we are encouraging older homeowners and their families to schedule counseling early, so that any delay does not affect decisions they need to make about their retirement."
Team Hinman will now discuss the counseling requirement during each initial consultation, before any application is started. The team will explain how to find HUD-approved counseling agencies, what documents homeowners should bring, and how the counseling certificate fits into the overall loan timeline. The practice will continue to review program costs and disclosures with each homeowner before closing.
The counseling issue comes as activity in the reverse mortgage market begins to recover. HECM World reported 1,995 FHA-insured HECM endorsements in October 2026, up 11.5 percent from September. That increase follows fiscal year 2026, when endorsements fell 14.2 percent to 24,182, the lowest annual total since 2003.
Retirement security remains a concern for many older Americans. An AARP study found that 69 percent of workers age 50 and older are concerned about having enough money to stay financially secure throughout retirement, and nearly six in ten said they worry about large unexpected expenses. For homeowners who have built equity over decades, a reverse mortgage for seniors is one of several options that may be considered alongside downsizing, a home equity line of credit, or other planning approaches.
Under program rules, all HECM borrowers must be at least 62 years old, and at least one must live in the home as a principal residence. Borrowers do not make monthly principal and interest payments but remain responsible for property taxes, homeowners insurance, applicable association dues, and maintenance. For calendar year 2026, HUD set the HECM maximum claim amount at $1,249,125 nationwide, and the 2027 figure is expected before the end of the year.
The counseling guidance is the second year-end advisory Team Hinman has issued this fall. In October, the practice released guidance on ITIN home financing, advising buyers who use an Individual Taxpayer Identification Number to confirm that the number is active before the December 31 expiration deadline. Both advisories deal with federal requirements that can delay a loan if they are not handled early.
For more information, visit Team Hinman or review the team's reverse mortgage options.
About Team Hinman
Team Hinman is a residential mortgage practice led by Jamie Hinman (NMLS #1074223), a mortgage specialist with more than 30 years of experience in home financing. The team works with homebuyers, homeowners, self-employed borrowers, investors, and retirees on purchase, refinance, home equity, and reverse mortgage financing. Its stated mission is to simplify the mortgage process through personalized guidance and clear communication. Equal Housing Opportunity. Loan programs, terms, and availability are subject to change and borrower qualification.
Jamie Hinman (NMLS #1074223) of Team Hinman. Equal Housing Opportunity. Loan programs, terms, and availability are subject to change and borrower qualification. This content is for informational purposes and does not constitute a commitment to lend.
###
For more information about Team Hinman, contact the company here:
Team Hinman
Jamie Hinman
(786) 2086293
jamie@teamhinman.com
1701 Ponce de Leon Blvd 4th Floor, Coral Gables, FL 33134, United States (but we have transferred to 9655 S Dixie Hwy Suite 200 Pinecrest, FL 33156)
If you believe this article contains misleading, harmful, or spam content, please let us know.
Report this articleMore News
View More
Recent Quotes
View MoreQuotes delayed at least 20 minutes.
By accessing this page, you agree to the Privacy Policy and Terms Of Service.