
Financial News
Leonardo DRS (NASDAQ:DRS) delivers impressive Q3 2026

Aerospace and defense company Leonardo DRS (NASDAQ: DRS) announced better-than-expected revenue in Q3 2026, with revenue up 11% year on year to $1.07 billion. The company expects the full year’s revenue to be around $3.97 billion, close to analysts’ consensus estimates. Its non-GAAP profit of $0.46 per share was 30.9% above analysts’ consensus estimates.
For more on Leonardo DRS, read our free full research report.
Leonardo DRS (DRS) Q3 2026 highlights:
- Revenue $1.07 billion vs S&P analysts’ consensus estimates of $1.02 billion (11% year-on-year growth, 4.1% beat)
- Adjusted EPS $0.46 vs S&P analysts’ consensus estimates of $0.35 (30.9% beat)
- Adjusted EBITDA $149 million vs analysts’ consensus estimates of $139.5 million (14% margin, 6.8% beat)
- Revenue guidance The company slightly lifted its revenue guidance for the full year to $3.97 billion at the midpoint from $3.94 billion
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $1.52 at the midpoint, an 11% increase
- EBITDA guidance $550 million at the midpoint for the full year, above analysts’ consensus estimates of $537.5 million
- Operating margin 10.9%, up from 9.7% in the same quarter last year
- Free cash flow margin 5.7%, down from 8% in the same quarter last year
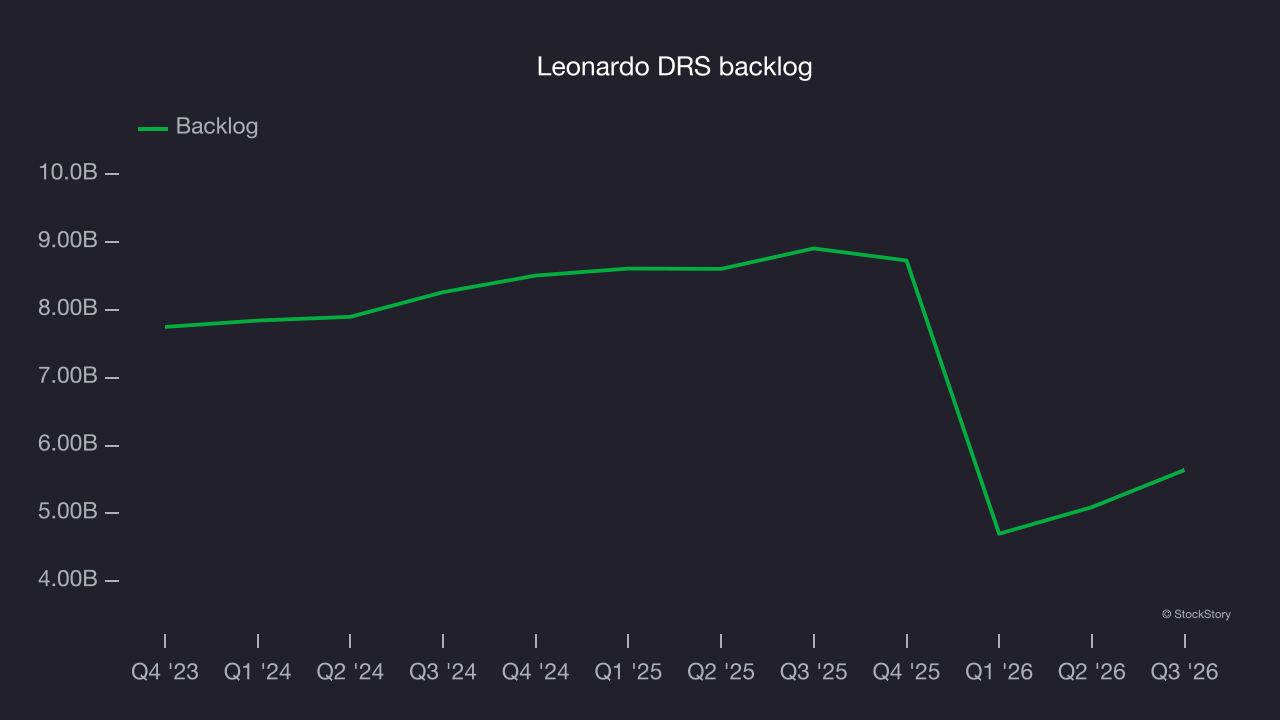
- Backlog $5.64 billion at quarter end, down 36.7% year on year
- Market capitalization $9.47 billion
CEO Commentary “Leonardo DRS delivered a strong third quarter, with 11% organic revenue growth and profitability growing even faster. Bookings exceeded $1.6 billion, representing a 1.5x book-to-bill ratio — both our strongest since becoming a public company four years ago. These results reinforce a strategy that is working — investing ahead of demand, in both differentiated capability and capacity, to help our customers maintain overmatch and enable us to scale when the mission requires it. Our record funded backlog, together with improved visibility into the fourth quarter, gives us confidence to raise and narrow our full-year revenue and profitability outlook,” said John Baylouny, president and CEO of Leonardo DRS.
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Even a poor business can perform well for one or two quarters, but a top-tier one grows for years. Leonardo DRS’s revenue grew at a mediocre 6.1% compounded annual growth rate over the last five years, an underwhelming result compared to the rest of the industrials sector. Still, there are things to like about Leonardo DRS.
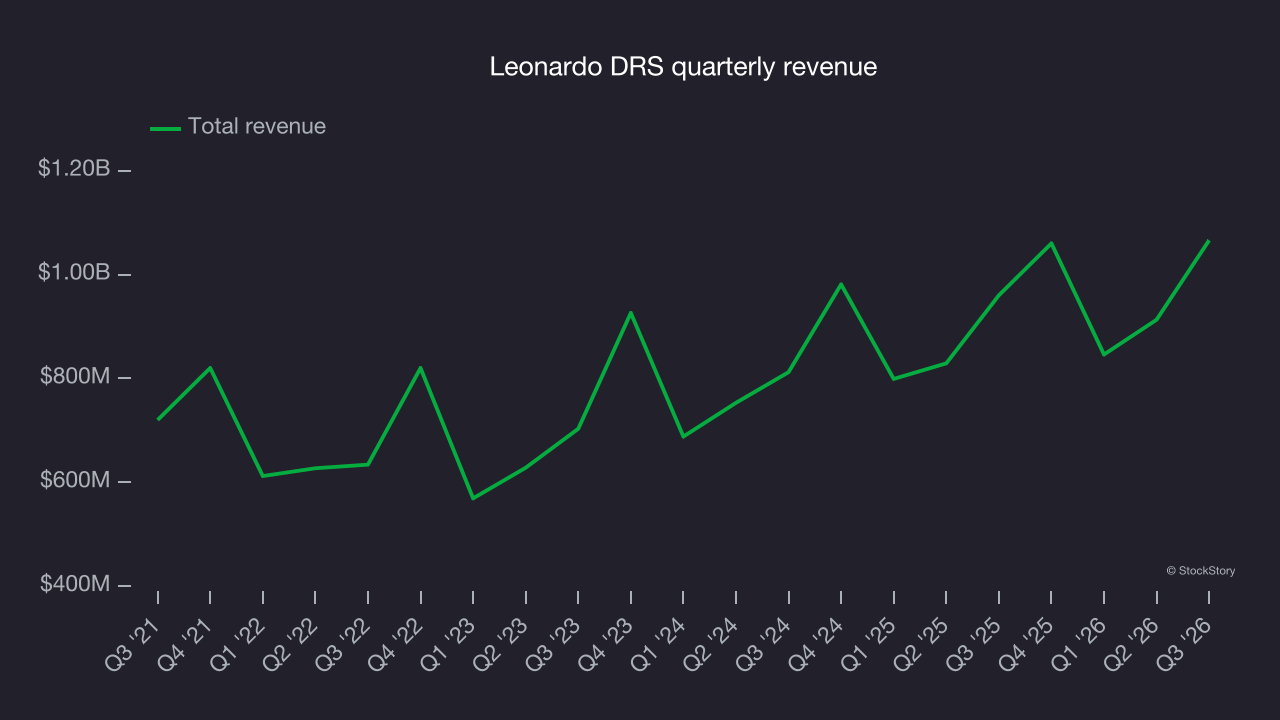
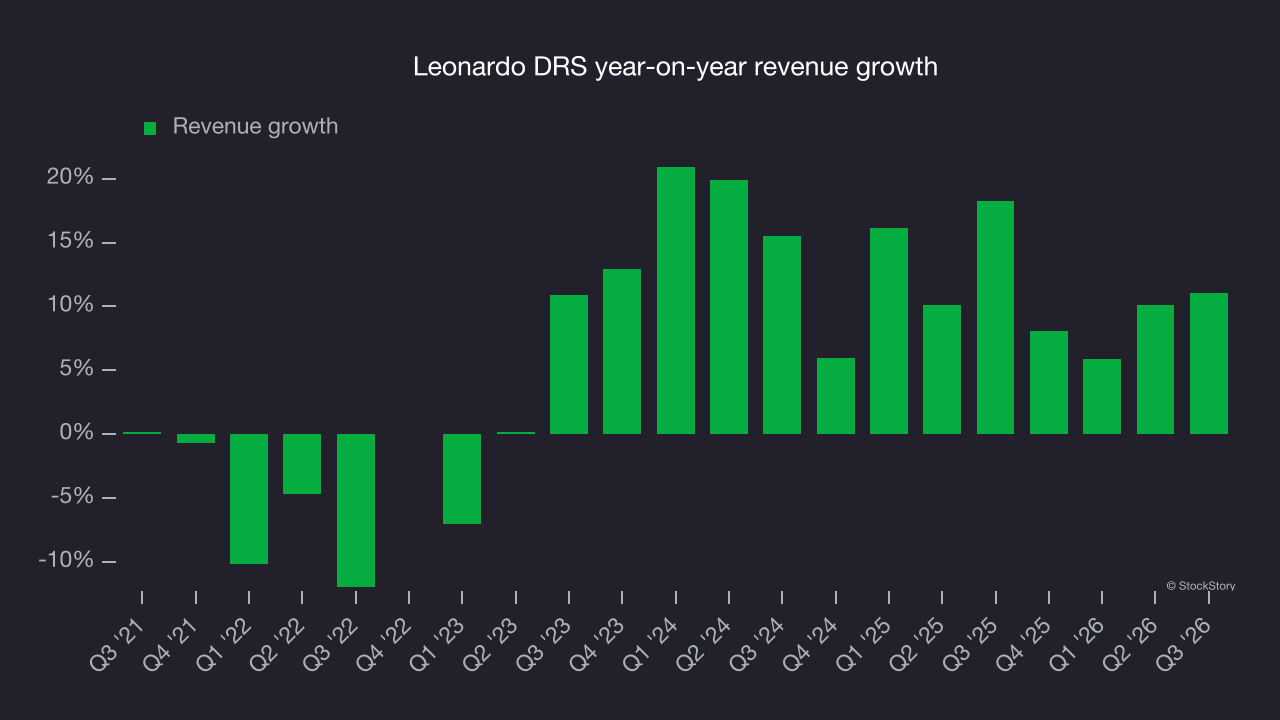
This quarter, Leonardo DRS reported year-on-year revenue growth of 11%, and its $1.07 billion of revenue exceeded Wall Street’s consensus estimates by 4.1%.
Looking ahead, sell-side analysts expect revenue to grow 5.7% over the next 12 months, according to S&P, a deceleration versus the last two years. This underwhelming projection suggests its products and services will face some demand challenges. On the positive side, the company is tracking well in other measures of financial health.
Operating margin
Leonardo DRS has managed its cost base well over the last five years. It demonstrated solid profitability for an industrials business, producing an average operating margin of 11.3%.
Looking at the trend in its profitability, Leonardo DRS’s operating margin decreased by 9.8 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
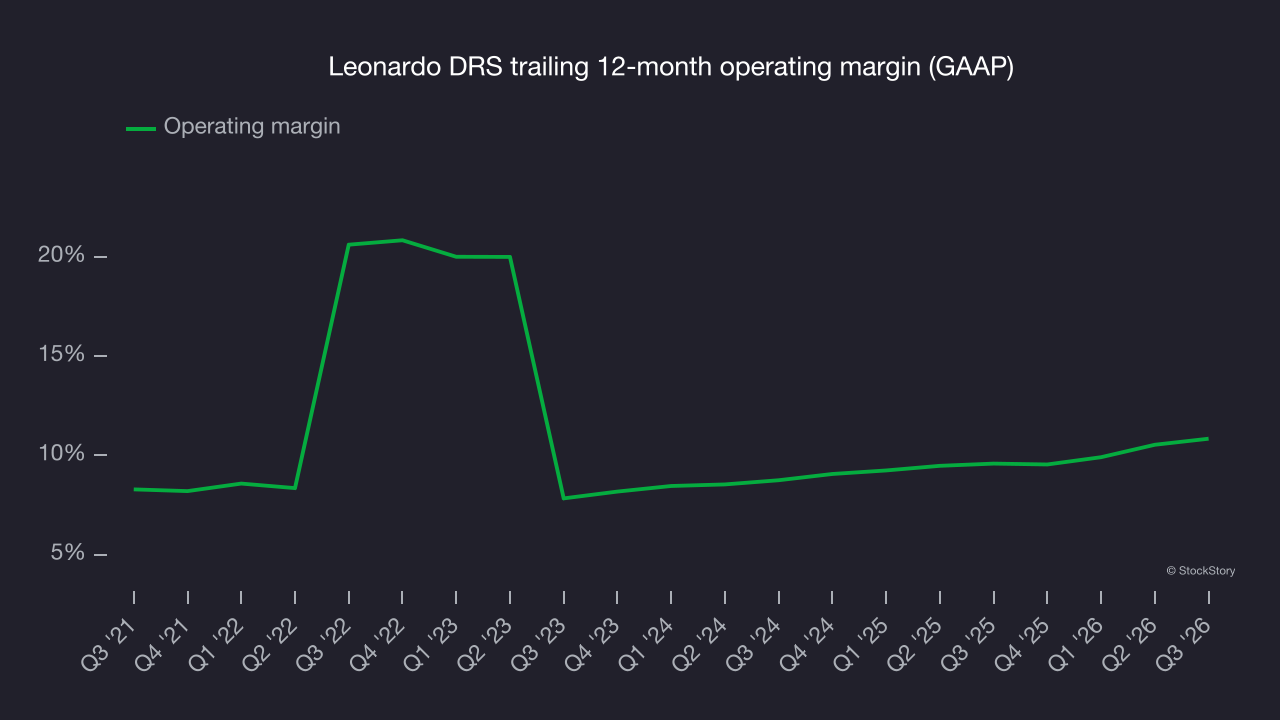
This quarter, Leonardo DRS generated an operating margin of 10.9%, up 1.2 percentage points year on year. This improvement shows it was more efficient.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Leonardo DRS’s full-year EPS grew at a strong 17.4% compounded annual growth rate over the last three years, better than the broader industrials sector.
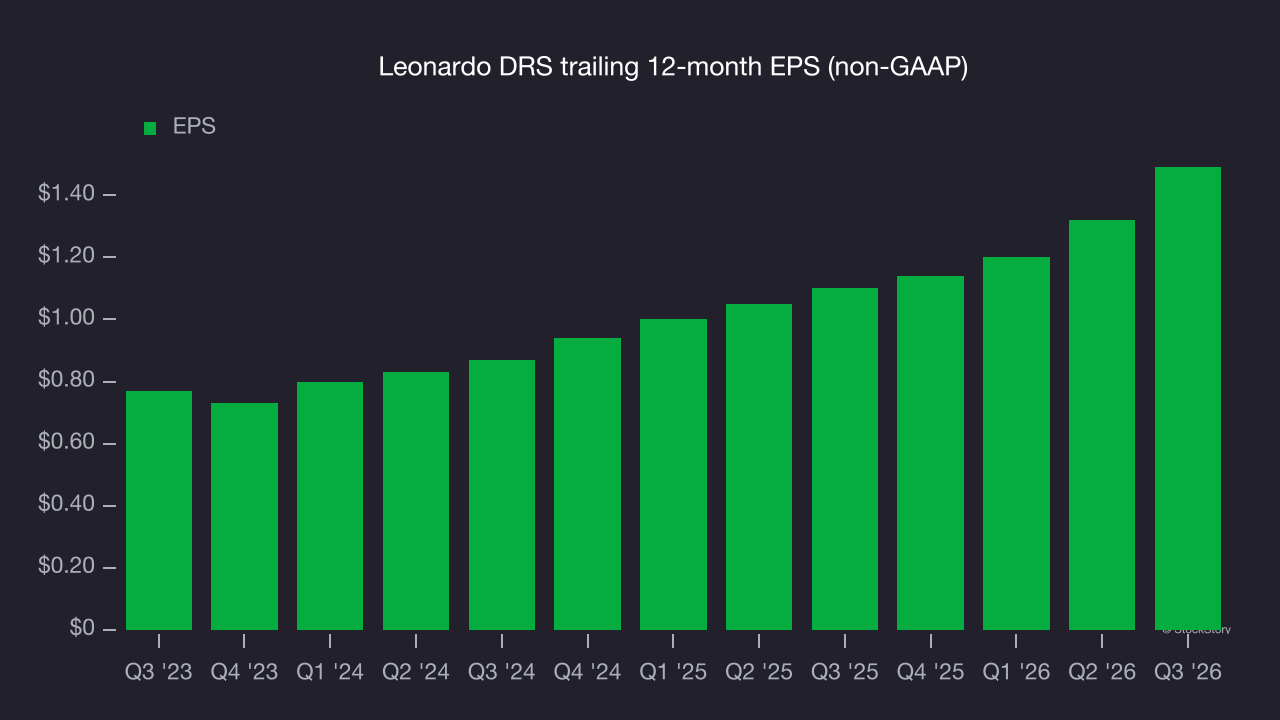
As with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Leonardo DRS, its two-year annual EPS growth of 30.9% was higher than its three-year trend. That acceleration is a positive sign, especially given the already high base.
In Q3, Leonardo DRS reported adjusted EPS of $0.46, up from $0.29 in the same quarter last year. This comfortably beat analysts’ consensus estimates, a positive result for shareholders. Over the next 12 months, Wall Street expects Leonardo DRS’s full-year EPS to shrink by 7.3% from $1.49 to $1.38, according to S&P.
Key takeaways from Leonardo DRS’s Q3 results
Leonardo DRS’s wide revenue beat stood out in a quarter with some important positives. EPS also topped analysts’ consensus estimates. Looking ahead, full-year revenue and EPS guidance were raised. Shares rose 4.4% to $37.06 immediately after the results.
Leonardo DRS had a solid quarter, but that alone doesn’t make the stock a buy. The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation when deciding whether to invest. Read the full research report here (it’s free).
If you believe this article contains misleading, harmful, or spam content, please let us know.
Report this articleMore News
View More
Recent Quotes
View MoreQuotes delayed at least 20 minutes.
By accessing this page, you agree to the Privacy Policy and Terms Of Service.